It has become difficult to keep up with all the news coming out of America. Trump’s erratic behaviour is combining with other factors to make the systematic risk picture complicated and unpredictable. On the one hand, there have been some excellent results coming out of the S&P500 companies riding the wave of AI.
AI Boom Lifts S&P 500 Earnings 32% as 86% of Companies Beat Estimates | Business | CryptoRank.io
Wall Street investors now expect that the earnings of the S&P500 companies will be roughly 32% higher than they were a year ago as second quarter earnings dramatically exceed analysts’ expectations. 86% of S&P500 companies have now reported earnings above forecast. Alphabet reported second-quarter earnings that included a $98 billion gain, while Amazon recorded $53.4 billion in non-operating pre-tax income, primarily related to its Anthropic investments. Nvidia’s revenue in the second quarter was $96,2bn – more than double the same quarter last year.
On the negative side, the price of North Sea Brent oil spiked up to nearly $110 per barrel last week, but has now fallen back to just below $100. This decline to $100 comes because of new hopes for peace negotiations such as planned meetings between Gulf and Iranian foreign ministers. These hopes helped ease immediate fears of a total, prolonged blockage of the Strait of Hormuz. At the same time, oil producers in the Persian Gulf shifted shipments to alternative pipeline capacities and non-Middle Eastern regions (like the US, Canada, and Ghana) which increased output to bridge supply gaps. Finally, major international bodies, including the International Energy Agency indicated that there was slowing consumption and a broader economic slowdown, and notably reduced oil demand from major importers like China driven partly by the transition to electric vehicles.
In the middle of all this, on Tuesday and Wednesday this week the US Federal Reserve Bank’s monetary policy committee will be meeting to decide on the future course of interest rates, and they will be focusing on these figures.
https://coinpaper.com/35641/stock-market-today-sp-500-nasdaq-jump-1-as-oil-falls-despite-hot-cpi
The US inflation rate for August 2026 came in at 3,4% for the year to the 31st August 2026. This was the same rate as July and shows broad increases across both goods and services with the price of gasoline being the major contributor. In the month itself, inflation was 0,4% because of a 3,9% increase in the price of gasoline.
Following hotter-than-expected August inflation data, market metrics and prediction venues show a massive shift toward monetary tightening. The CME Fedwatch Tool suggests that the probability of a 25 basis point hike in interest rates is now between 84% and 87% while Polymarket says there is an 81% probability. A hike in interest rates will add to the misery of consumers in America already facing an average price across the country of $4.30 per gallon of petrol.
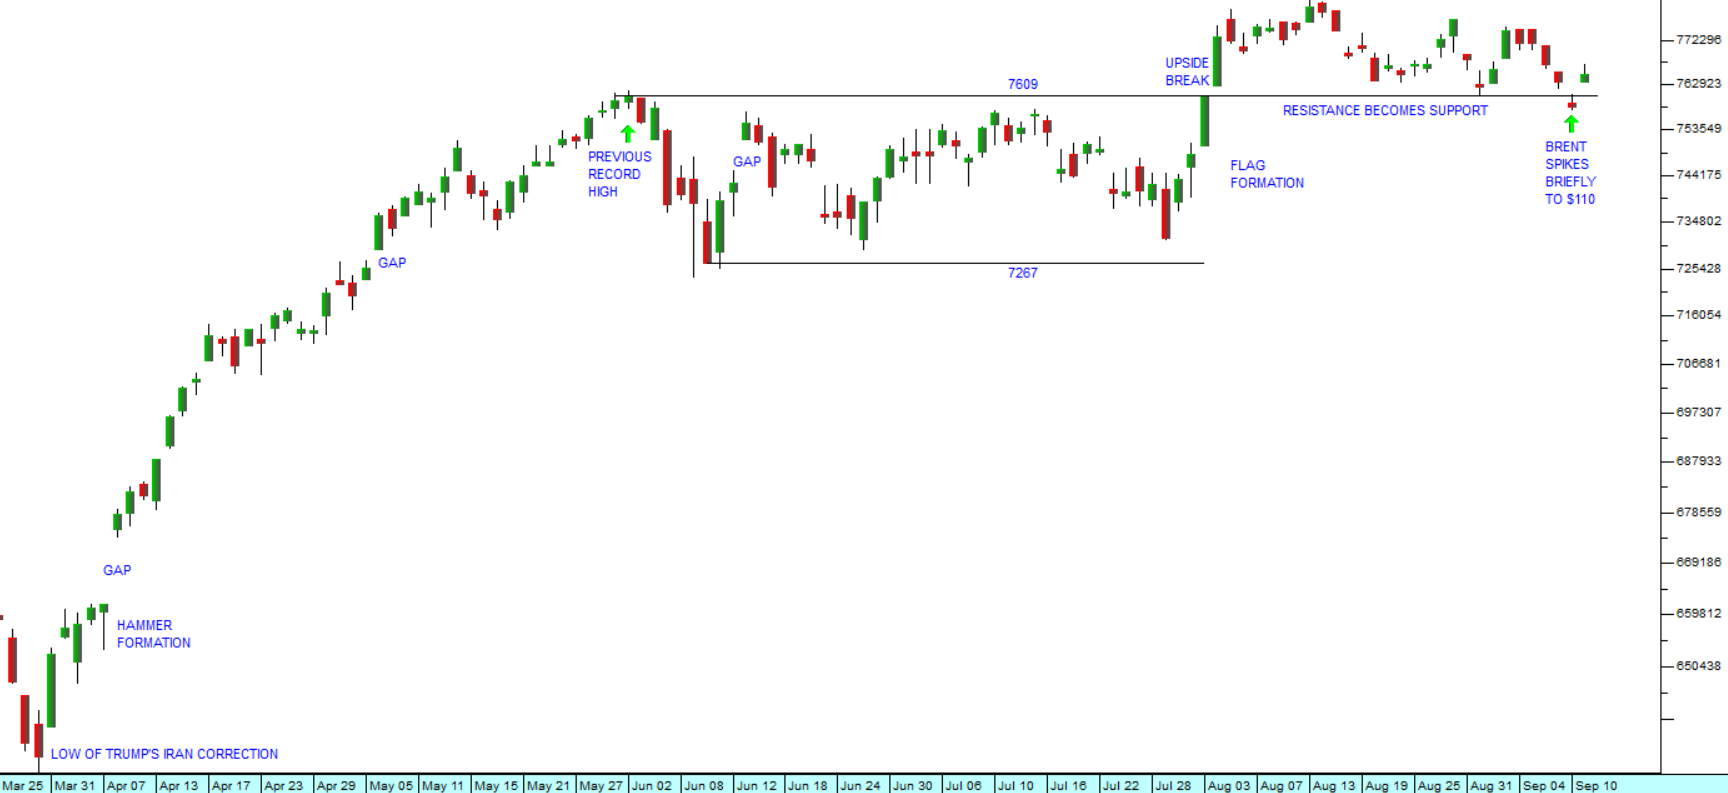
The S&P500 index has been trying to discount all these disparate forces and is basically moving sideways since it broke above the key support/resistance level at 7609. Consider the chart:
 S&P500 Index : 25th March 2026 - 11th of September 2026. Chart by ShareFriend Pro.
There can be little doubt about the bullish sentiment which underlies the extended sideways market in the S&P. The news coming from big tech companies appears to be slowly overcoming the bad news coming out of the Middle East. The unexpected spike in the oil price to $110 was short-lived, but it did unnerve the market for a day. That was quickly rectified the next day.
And in the background is the looming mid-term election in America, which is increasingly focusing the Trump camp’s attention, resulting in some radical moves on his part like promising to pay every adult American $5000 if the Republicans win both the House and the Senate. The cost of this is a further $1,23 trillion to be added to the budget deficit already above $40 trillion. He also said that after the elections the petrol price will drop back to $2 per gallon – and anyone who believes that is not following what is happening on the ground.
Trump approval rating hits new low over Labor Day weekend
The Focaldata/Financial Times poll released on September 6, 2026, found that only 32% of Americans now approve of Trump's job performance. Trump's approval rating dropped three points from the previous month, the lowest since the poll series began in May. Critically, his approval among Republicans fell to 72%, a two‑point decline and a new low for that group. The poll was conducted from August 28 to September 2 with 2,178 U.S. adults surveyed. Only 17% of respondents approved of Trump's handling of inflation and the cost of living, while 69% disapproved.
In our view, the Republicans will almost certainly lose the House and the Senate race is now a “toss-up”. If he loses both, we can expect impeachment proceedings to commence promptly.
The S&P500 and markets around the world will ultimately be drawn higher by the AI driven boom in American and elsewhere. We expect new record highs on all indexes in due course.