Market View
J200 99,394.00 -1.75% J203 107,104.00 -1.63% J210 115,917.00 -2.32% J211 117,098.00 -0.51% J212 24,346.00 -2.23% J213 131,148.00 -1.46%
Winning Shares (Top 5)
Code Name Added Price Latest % Gain % Gain/Year
REM REMGRO 2025-07-03 16422 20000 +21.79% +17.25%
CLH CITYLDG 2025-11-07 436 441 +1.15% +1.25%
SBP SABCAP 2024-09-27 8100 14300 +76.54% +37.75%
S32 SOUTH32 2025-12-02 3715 5702 +53.49% +63.18%
AEL ALTRON-A 2026-04-15 2199 2755 +25.28% +52.74%
Opinions (Top 5)
Code Name Date Action
AFT AFRIMAT 2026-10-08 View

08-10-2026   Afrimat (AFT) is an open-pit mining company that supplies composites, construction materials and other commodities to a range of industries in Southern Africa. Until the end of 2015, Afrimat was one of the best performing shares on the JSE. The share broke up out of a 3-year sideways pattern which included the COVID-19 crisis.

The company benefited from rising iron ore prices due to supply constraints in Brazil and rising demand from China. On 17th August 2020, the company announced that it had bought a mining exploration company (Coza Mining) involved in looking for iron and manganese in the Northern Cape for R300m.

On 20th March 2022 the company announced that its listing had been moved from Basic Materials Construction and Materials to the General Mining sector which better reflected its business.  In its results for the year to 28th February 2026 the company reported revenue up 20,3% and headline earnings per share (HEPS) up 32,5%. The company said, "Afrimat remains profitable, with operating profit which increased by 9.6% to R523,7 million (FY2025: R477,7 million).

The increase in the cost of sales is primarily due to higher-than-normal repairs and maintenance in the Cement business to improve the performance of the plant". In a pre-close update on the first quarter the company reported, "...reduced Rand-denominated iron ore export revenues at mine gate, driven by a stronger Rand, lower international iron ore prices and significantly higher shipping rates".

In a trading statement for the six months to 31st August 2026 the company estimated that it would make a headline loss of between 55c and 60c per share compared with a profit of 101,9c in the previous period. The company said, "The primary driver of the decline in profitability during the period was iron ore.

Export revenue was adversely impacted by a combination of a stronger Rand and significantly higher shipping costs (49.1%) due to disruptions from the Iran conflict". Like all commodity companies, Afrimat's shares have declined with the drop in commodity prices, but this company is well diversified making it less risky. The share has broken down through support at around 3400c and looks to fall further.

We suggest waiting for a clear break up through the long-term downward trendline before investigating further. 

OMN OMNIA 2026-10-08 View

08-10-2026   Omnia (OMN) is a diversified chemicals company supplying products to the agricultural, chemicals and mining industries in South Africa and 48 other countries. The Agricultural division is the leader in fertilizers in Southern Africa. It supplies granular, liquid and speciality fertilizers in Southern Africa, Eastern Africa, Australia, New Zealand, and Brazil.

The mining division is the leading supplier of explosives in South Africa, Mali, Swaziland, Sierra Leone, Malawi, Senegal, Zambia, Zimbabwe, Botswana, Mozambique, and the DRC. The chemicals division is a manufacturer and distributor of speciality, functional and effect chemicals and polymers operating throughout the African continent.

The company gets most of its sales from agriculture for fertilizers and the mining industry for explosives. In its efforts to diversify away from the South African economy, OMN acquired Oro Agri in America for $100m and Umongo Petroleum for R780m. They also commenced the construction of a R630m nitro phosphate plant at Sasolburg.

This company's performance reflects the general performance of the South African economy. It has been very well managed and grows consistently by acquisition and organically, but it is in very tough markets where it has become difficult to make good profits. It is a relatively risky investment and dependent on commodity prices and agriculture - but both of which have done well.

In its results for the year to 31st March 2026 the company reported revenue up 6% and headline earnings per share (HEPS) up 21%. The company said, "This was driven by strong volume and margin growth, supported by the strengthening competitiveness of our core businesses, with both Agriculture and Mining contributing robust earnings, margins and solid cash generation".

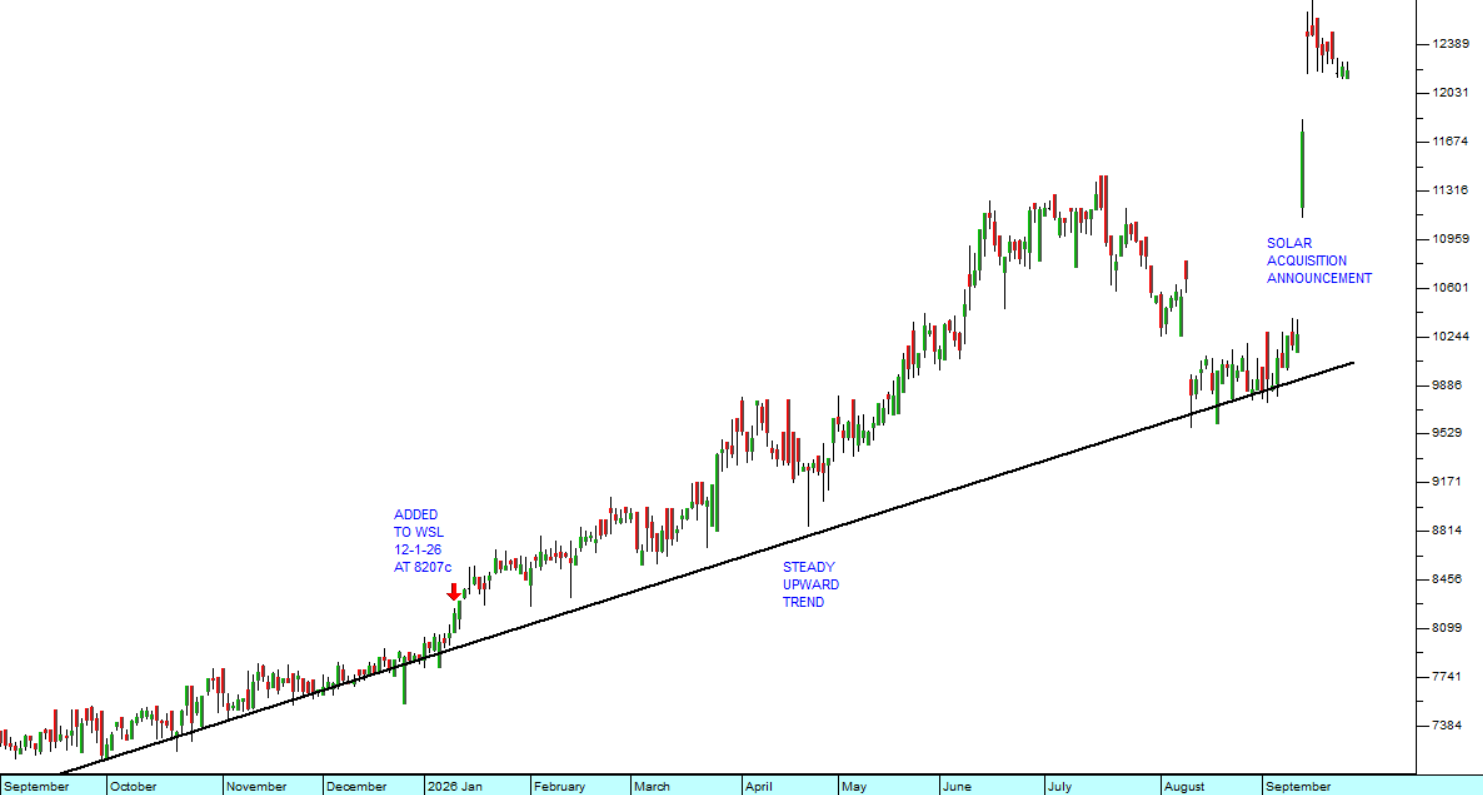
Technically, the share was in a downward trend from its peak in May 2022. We recommended waiting for it to break up through its long-term downward trendline, which happened on 18th June 2024 at 6087c and then the share was added to the Winning Shares List (WSL) on 12th January 2026 at 8207c.

The share has since moved up to 10486c (8-6-26). On the 14th of September 2026 the company announced that it had received a firm offer to buy all of its ordinary shares for R21,8bn or 13450c per share. The announcement caused the share price to jump up. Omnia shares are expected to be delisted from the JSE on 29th June 2027.

TLM TELEMASTR 2026-10-07 View

Telemaster(TLM) is a company which supplies voice, data and cloud communications using fixed line, fixed cellular, fixed data, and PBX services. It has three divisions - voice, cloud PBX and internet. The business consists of (1) Catalytic Connections (Pty) Limited is a diversified ICT managed solutions provider to medium and small enterprises.

(2) Contineo Virtual Communications (Pty) Limited operates a Next Generation Unified Communications (“UC”) platform based on Cisco Broadsoft technology. (3) PerfectWorx Consulting (Pty) Limited is a niche network systems integrator. (4) Ultra Data Centre (Pty) Limited built and operates a data centre located outside of Pretoria.

In its results for the six months to 31st December 2025 the company reported revenue up 13,62% and headline earnings per share (HEPS) up 94,29%. In a trading statement for the year to 30th June 2026 the company estimated that HEPS would increase by 334% to 4,69c. The share is very thinly traded with less than R1000 worth of shares changing hands each day because most of the shares are held by a single shareholder - the Maison D-Obsession truSt. This makes it impractical for private investors. 

SRE SIRIUS 2026-10-06 View

06-10-2026 Sirius (SRE) is a real estate investment trust (REIT), listed on the JSE and the London Stock Exchange (LSE), which specialises in office, manufacturing, and warehousing properties in Germany. The company owns 141 assets with a book value of about 2bn euros. Obviously, this is a well-managed and growing rand-hedge which was benefiting directly from the recovery of the German economy before COVID-19.

The company has formed a joint venture (JV) with AXA Investment Managers in terms of which AXA will own 65% and Sirius will own 35%. The JV (called "Titanium") acquired 5 business parks from Sirius for 168m euros - which is a 19% premium to their book value. The JV will allow Sirius to double the value of its assets over the next two years.

In its results for the year to 31st March 2026 the company reported an 8,4% increase in funds from operations and headline earnings per share (HEPS) down 18,6%. The company said, "Cash at bank of €372.7m (2025: €571.3m) and €300m undrawn revolving credit facility, providing abundant liquidity ahead of the repayment of the €400.0m bond due in June 2026.

• 36.1% net LTV (2025: 31.4%) and Net Debt to EBITDA of 6.6x (2025: 5.2x)". In a trading update for the six months to 30th September 2026 the company reported its rent roll up 11,3% and the repayment of 400m euros of a corporate bond debt. The company said, "Sirius has delivered a strong period of double digit rent roll growth, nearly half of which has been organic". Technically the share has been falling and so investors should exercise caution.

At current levels, it is on an earnings multiple of 14,88 - which makes it one of the most highly rated REIT's on the JSE and therefore possibly vulnerable. It is also, obviously, a rand hedge. 

SNT SANTAM 2026-10-06 View

06-10-2026 Santam (SNT) is South Africa's largest short-term insurer with about 22% of the market. This means that it does not engage in endowment insurance, annuities or any kind of investment insurance. It insures assets, like buildings and vehicles and individuals against risks which they cannot afford such as the loss of their income through disability or death.

Santam pays the first R150m of any claim and then relies on its re-insurance policy. The company has level 1 BEE status and employs more than 6000 people. Following the Ma-Afrika judgement, Santam has increased its provision for contingent business interruption (CBI) by R1,7bn. Santam rates as one of the JSE's most reliable quality shares.

The company was obviously impacted by the civil unrest in July 2021. In its results for the six months to 30th June 2026 the company reported return on shareholders funds of 27% - down from the 33% reported in the previous period. Headline earnings per share (HEPS) were 1991c compared with 1885c in the previous period.

The share trades on a P:E of 10,8. It is probably the best example of a blue-chip share, with a strong balance sheet and a history of steadily improving earnings, year after year, for many years and its latest results were unusually good. These facts can be seen in the steady upward trend of its share price over the past 39 years.

In 1985 the share traded for 90c and today it trades for around R404 (3-9-26). This share should be a part of any private investor's portfolio. On 5th October 2026 Business Day reported that Sanlam had a plan to buy out this minorities in Santam, which it already owns 63% of, for R505 per share and delist it.

This had an immediate impact on the share price causing it to jump up almost 20%.

Winning Share: CLH
Opinion: OMN
The Omnia Takeover  (2026-09-28)

Omnia is a manufacturer of chemicals used in agriculture (fertilisers), mining (explosives) and various industries. It operates primarily in South Africa, but its products are sold throughout Southern Africa and abroad. In its latest financial statements for the year to 31st March 2026 the company…

Omnia is a manufacturer of chemicals used in agriculture (fertilisers), mining (explosives) and various industries. It operates primarily in South Africa, but its products are sold throughout Southern Africa and abroad.

In its latest financial statements for the year to 31st March 2026 the company reported revenue up 6% and headline earnings per share (HEPS) up 21%. The company benefited in some ways from the war in Iran and the closure of the Strait of Hormuz because that restricted the flow of agricultural chemicals onto world markets resulting in higher prices. Omnia was able to pay a dividend of 470c for the year, plus a special dividend of 280c. During the year it also bought back and cancelled 187436 of its own shares at an average price of 6465c per share returning a further R12,1m to shareholders.

This is one of the companies that was very hard hit by the COVID-19 pandemic, and its share price fell to a low of 1536c in May 2020. We published an article about it on 2nd September 2019, drawing attention to the fact that it had been consistently trading well below its net asset value (NAV) for some time. Obviously, when a profitable listed company trades below its NAV, it generally becomes a potential take-over target for both local and international investors.

For the next five years Omnia continued to strengthen and diversify its position. By March this year it was growing profits in all divisions and had a strong balance sheet. This attracted the attention of a large international chemicals company operating out of India, The Solar Group, who have now made an offer to buy 100% of Omnia’s ordinary shares for 13450c each. Omnia will delist from the JSE once the acquisition scheme by Solar SA Investments is implemented.

The cautionary announcement was published on the Stock Exchange News Service (SENS) on 11th September this year and the share price immediately rose sharply in response. The fact that it did not rise earlier indicates that there was little or no insider trading associated with this announcement. Consider the chart:

Omnia (OMN) : September 2025 - 25th of September 2026. Chart by ShareFriend Pro.

In anticipation of good results at the year-end in March 2026, we added Omnia to the Winning Shares List (WSL) on 12th January 2026 at a price of 8207c per share. At the time we felt that the company was trading well below its value given its track record and performance.

The Solar Group sells its products in 90 countries around the world and has manufacturing facilities in 11 countries. There are considerable synergies flowing from the acquisition, especially considering that Solar does not appear to be in agricultural sector. Omnia’s expertise and product knowledge will add considerably to the group over time.

Taking into account that an investor would have received 750c in dividends, the decision to buy into Omnia when we added it to the WSL would have yielded a return of 13450c + 750c – 8207c = 5993c or 73% in a period of much less than a year. Altogether a very satisfactory investment!

Using AI  (2026-09-21)

Artificial Intelligence (AI) has been sweeping the world over the past year affecting almost every field of human endeavour. The investment world is no exception. Today the private investor, through AI, has access to a range of analysis which is totally unprecedented and lightning fast. For example…

Artificial Intelligence (AI) has been sweeping the world over the past year affecting almost every field of human endeavour. The investment world is no exception. Today the private investor, through AI, has access to a range of analysis which is totally unprecedented and lightning fast. For example, if you pose the following to Google's Gemini:

“Using a price:earnings growth ratio (PEG), with historical earnings figures over the past 10 years, compare Clicks and Dischem on the JSE for relative value at their current prices”.

A few seconds later, you will receive the following answer:

Based on a 10-year historical valuation framework using the Price/Earnings-to-Growth (PEG) metric, Clicks Group Limited (CLS) offers significantly better relative value than Dis-Chem Pharmacies Limited (DCP), with Clicks holding a PEG ratio of 1,07 compared to Dis-Chem's elevated PEG ratio of 4,92. While both healthcare retailers have faced growth pressures over the past year, Clicks’ consistent long-term earnings growth profile maps to a far more sustainable valuation at current market prices.

It then goes on to say:

To understand the core drivers behind these valuation gaps, we normalize the current trailing Price-to-Earnings (P/E) ratios against their respective multi-year historical Compound Annual Growth Rates (CAGR) in Headline Earnings Per Share (HEPS).

Clicks Group (CLS) — Steady Compounder

  • Robust Growth Track Record: Over the past decade, Clicks Group has compounded its diluted HEPS at an impressive 13,5% per annum, alongside a dividend growth rate of 14,2%.
  • Defensive Cost Efficiencies: Its massive retail presence (~1,000 stores) gives it exceptional operating leverage. At a current P/E of 14,45x, the market has compressed Clicks' historical premium rating (which typically sat closer to 30x), creating a much safer entry point where the earnings growth rate almost directly mirrors its multiple.

Dis-Chem Pharmacies (DCP) — Growth Disruption

  • Earnings Volatility: While Dis-Chem Pharmacies initially listed with immense growth premium expectations in 2016, its long-term financial delivery has slowed down. For instance, its FY2026 annual performance saw a sharp 17,3% drop in HEPS to 113,7 cents due to significant operational and macroeconomic pressures.
  • Depressed Growth Base: Compounding its HEPS from its first full year post-listing (74,7 cents in FY2017) to FY2026 yields a long-term compound growth rate of only 4,78%. A P/E multiple of 23,53x is highly mismatched against this lower single-digit structural growth pace, heavily inflating its PEG ratio.

Risk Guardrails & Framework

Peter Lynch’s traditional benchmark dictates that a PEG ratio near 1,0 indicates a stock is fairly priced relative to its growth, while any metric significantly exceeding 2,0 alerts investors to potential overvaluation relative to realized history. For long-term portfolios, Clicks presents a structurally sound baseline where you are paying a reasonable price for a stable, high-return business framework, whereas Dis-Chem requires aggressive operational margin expansions (such as its automated staffing framework 2.0 initiatives) to justify its present multiple.

This analysis shows that Clicks is cheap at current prices, while Dischem is probably over-priced. Of course, you could have come to the same conclusion if you had done the work yourself, but that would be extremely laborious and time-consuming. For many months now we have been watching Clicks closely. Its price has virtually halved since the middle of last year. And when the price of a blue chip share like Clicks halves, it is always worth investigating.

Of course, before you know to ask such a question you would need to have a basic understanding of how the PEG ratio works or even that there is such a thing as the PEG ratio. Even with the advantage of AI, you need to know enough to be able to ask the right questions – but AI can help you with that too.

We are not suggesting that you let AI make your investment decisions, but we are suggesting that when you find an investment idea it can be a very powerful tool for analysis.

And we do believe that Clicks offers significant value at current levels. Certainly, we believe that it is far better value than Dischem. That is why we asked AI the question in the first place.

Muddy Waters  (2026-09-14)

It has become difficult to keep up with all the news coming out of America. Trump’s erratic behaviour is combining with other factors to make the systematic risk picture complicated and unpredictable. On the one hand, there have been some excellent results coming out of the S&P500 companies riding…

It has become difficult to keep up with all the news coming out of America. Trump’s erratic behaviour is combining with other factors to make the systematic risk picture complicated and unpredictable. On the one hand, there have been some excellent results coming out of the S&P500 companies riding the wave of AI.

AI Boom Lifts S&P 500 Earnings 32% as 86% of Companies Beat Estimates | Business | CryptoRank.io

Wall Street investors now expect that the earnings of the S&P500 companies will be roughly 32% higher than they were a year ago as second quarter earnings dramatically exceed analysts’ expectations. 86% of S&P500 companies have now reported earnings above forecast. Alphabet reported second-quarter earnings that included a $98 billion gain, while Amazon recorded $53.4 billion in non-operating pre-tax income, primarily related to its Anthropic investments. Nvidia’s revenue in the second quarter was $96,2bn – more than double the same quarter last year.  

On the negative side, the price of North Sea Brent oil spiked up to nearly $110 per barrel last week, but has now fallen back to just below $100. This decline to $100 comes because of new hopes for peace negotiations such as planned meetings between Gulf and Iranian foreign ministers. These hopes helped ease immediate fears of a total, prolonged blockage of the Strait of Hormuz. At the same time, oil producers in the Persian Gulf shifted shipments to alternative pipeline capacities and non-Middle Eastern regions (like the US, Canada, and Ghana) which increased output to bridge supply gaps. Finally, major international bodies, including the International Energy Agency indicated that there was slowing consumption and a broader economic slowdown, and notably reduced oil demand from major importers like China driven partly by the transition to electric vehicles.

In the middle of all this, on Tuesday and Wednesday this week the US Federal Reserve Bank’s monetary policy committee will be meeting to decide on the future course of interest rates, and they will be focusing on these figures.

https://coinpaper.com/35641/stock-market-today-sp-500-nasdaq-jump-1-as-oil-falls-despite-hot-cpi

The US inflation rate for August 2026 came in at 3,4% for the year to the 31st August 2026. This was the same rate as July and shows broad increases across both goods and services with the price of gasoline being the major contributor. In the month itself, inflation was 0,4% because of a 3,9% increase in the price of gasoline.

Following hotter-than-expected August inflation data, market metrics and prediction venues show a massive shift toward monetary tightening. The CME Fedwatch Tool suggests that the probability of a 25 basis point hike in  interest rates is now between 84% and 87% while Polymarket says there is an 81% probability. A hike in interest rates will add to the misery of consumers in America already facing an average price across the country of $4.30 per gallon of petrol.

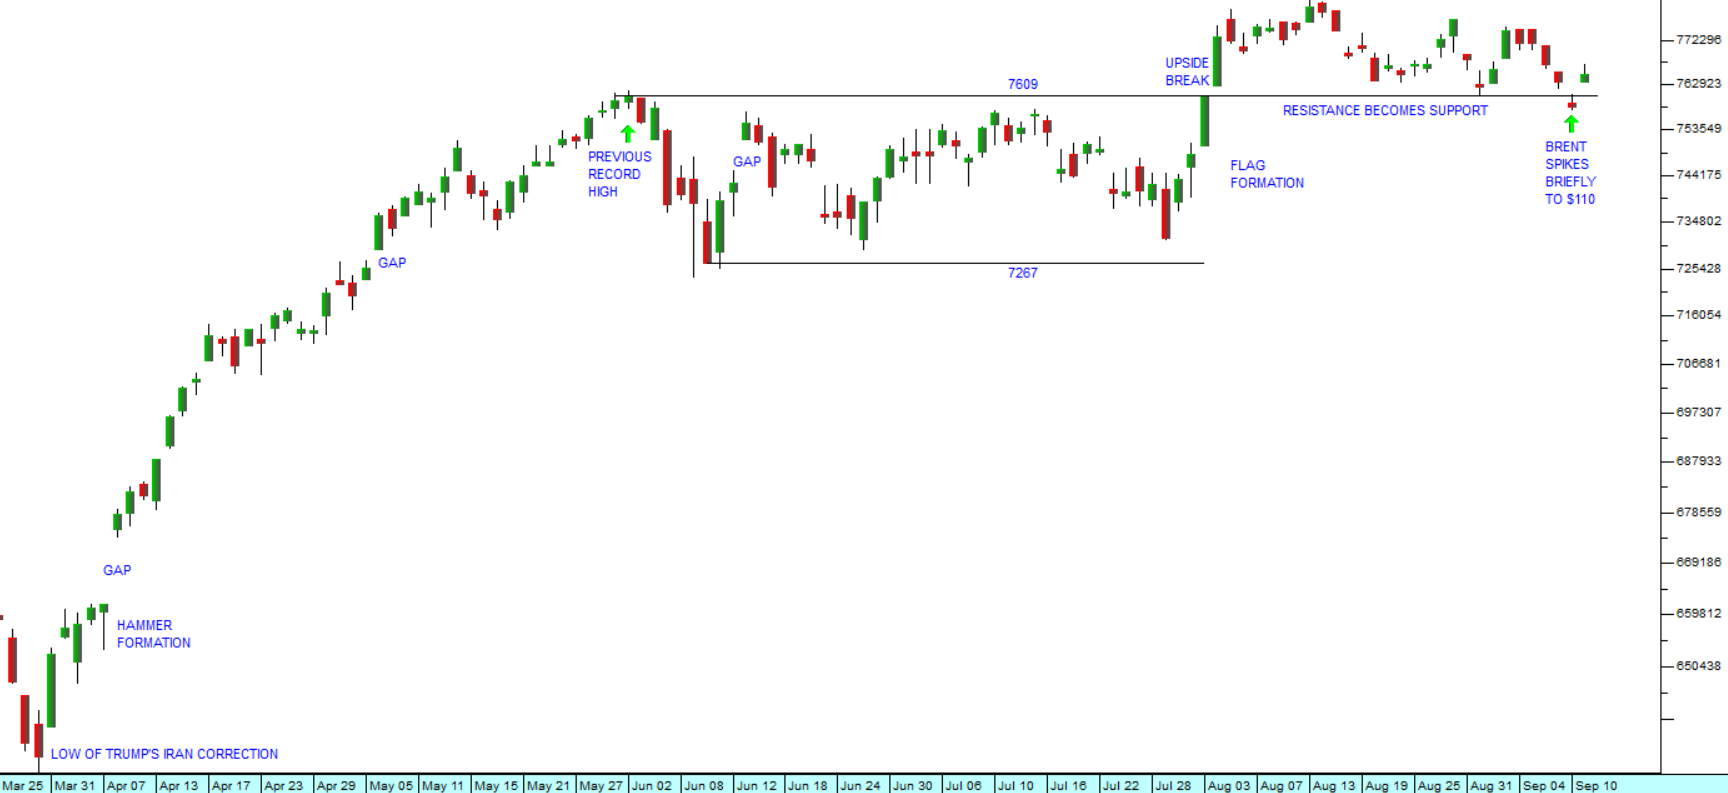
The S&P500 index has been trying to discount all these disparate forces and is basically moving sideways since it broke above the key support/resistance level at 7609. Consider the chart:

S&P500 Index : 25th March 2026 - 11th of September 2026. Chart by ShareFriend Pro.

There can be little doubt about the bullish sentiment which underlies the extended sideways market in the S&P. The news coming from big tech companies appears to be slowly overcoming the bad news coming out of the Middle East. The unexpected spike in the oil price to $110 was short-lived, but it did unnerve the market for a day. That was quickly rectified the next day.

And in the background is the looming mid-term election in America, which is increasingly focusing the Trump camp’s attention, resulting in some radical moves on his part like promising to pay every adult American $5000 if the Republicans win both the House and the Senate. The cost of this is a further $1,23 trillion to be added to the budget deficit already above $40 trillion. He also said that after the elections the petrol price will drop back to $2 per gallon – and anyone who believes that is not following what is happening on the ground.

Trump approval rating hits new low over Labor Day weekend

The Focaldata/Financial Times poll released on September 6, 2026, found that only 32% of Americans now approve of Trump's job performance. Trump's approval rating dropped three points from the previous month, the lowest since the poll series began in May. Critically, his approval among Republicans fell to 72%, a two‑point decline and a new low for that group. The poll was conducted from August 28 to September 2 with 2,178 U.S. adults surveyed. Only 17% of respondents approved of Trump's handling of inflation and the cost of living, while 69% disapproved.

In our view, the Republicans will almost certainly lose the House and the Senate race is now a “toss-up”. If he loses both, we can expect impeachment proceedings to commence promptly.

The S&P500 and markets around the world will ultimately be drawn higher by the AI driven boom in American and elsewhere. We expect new record highs on all indexes in due course.

JSE Top 40

99,394.00 (-1.75%)

All Share

107,104.00 (-1.63%)

Financial 15

24,346.00 (-2.23%)

J200
J203
J212
Top Gainers
# Code Name Close (c) % move
1 OAO OANDO 30 +50.00%
2 NRL NEWPARK 700 +34.62%
3 PPR PUTPROP 998 +33.96%
Top Losers
# Code Name Close (c) % move
1 RBO RAINBOW 501 -22.20%
2 YRK YORK 190 -9.52%
3 MKR MNTKRENEW 4400 -8.88%

Top Movers – Charts

Top Gainer: OAO
Top Loser: RBO