Every major event that happens in the world inevitably offers some kind of investment opportunity for the private investor. The challenge is to work out how best to capitalise on it. So, it was with the war in Iran.
At the time that the war began with the Israeli and American bombing raids on 28th February 2026, we had already been watching the progress of Sasol for some time. The situation in Iran was tense with riots reported and North Sea Brent had climbed back up to $70 per barrel, but we had no idea that the Americans and Israelis were about to launch a bombing attack.
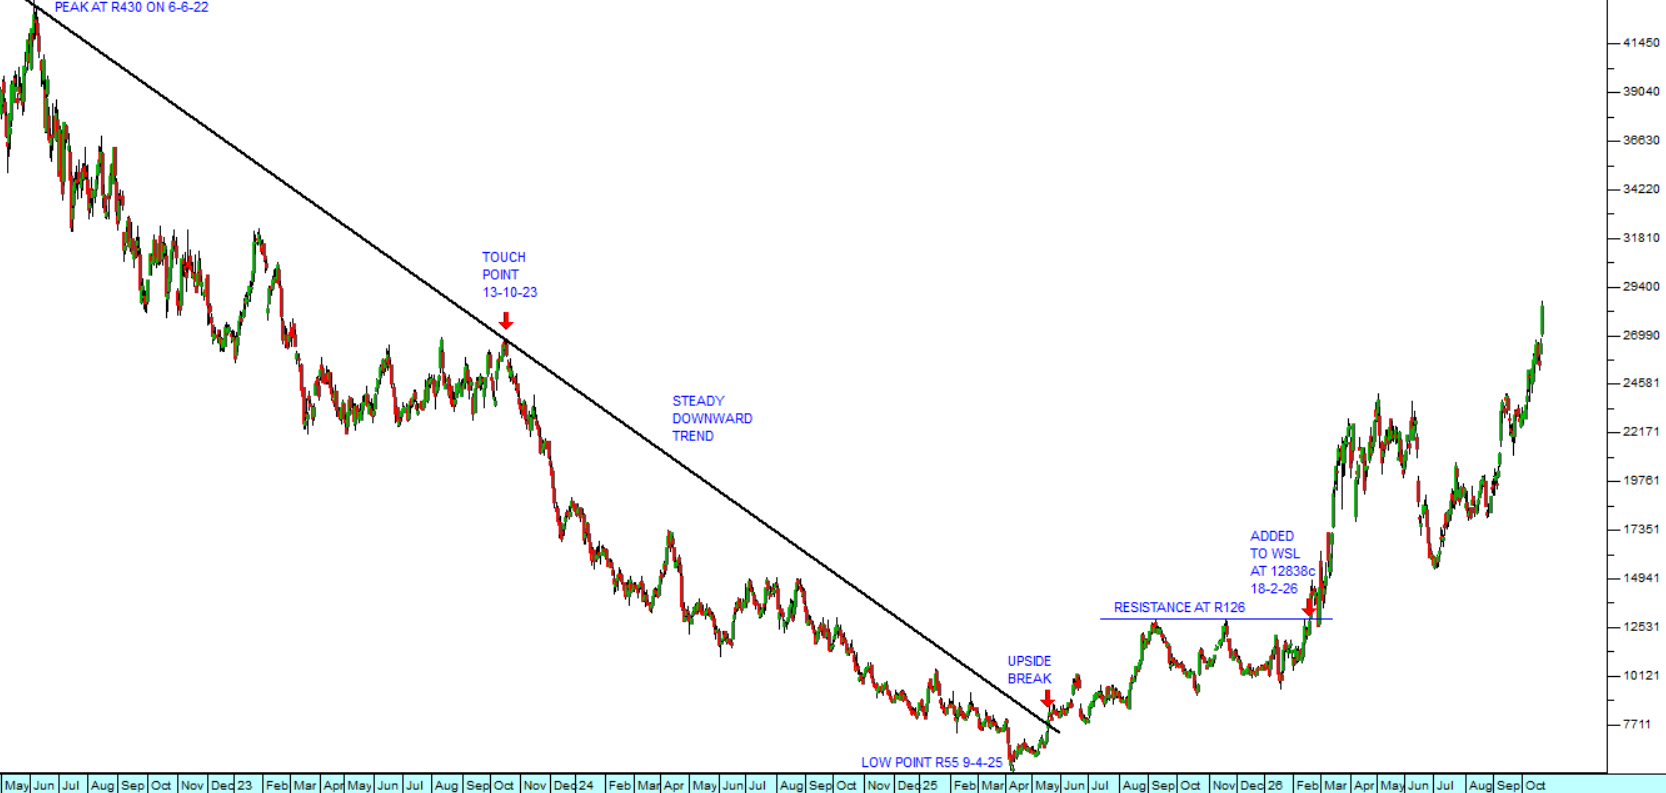
Sasol was always a blue-chip share and has historically occupied a dominant position in South Africa's synthetic fuels industry. It had, however been through some difficult times and the share price had fallen from a high of R430 per share to as low as R55 in April 2025. It then went through an extended period of sideways consolidation. We finally decided to add it to the Winning Shares List (WSL) on 18th February 2026 at a price of R128.36. Technically the share broke above resistance at R126 indicating that something was afoot. Consider the chart:
 Sasol (SOL) : May 2022 - 23rd of October 2026. Chart by ShareFriend Pro.
The chart shows Sasol’s long downward trend that began in the middle of 2022, mainly because of the falling price of various grades of oil. North Sea Brent oil fell from a high of $125 per barrel on 8th March 2022 to its cycle low just below $60 per barrel in mid-December 2025. Since Sasol derives more than half of its revenues and profits from the fuel industry, it is directly linked to the price of oil.
Sasol had been recovering but had encountered significant resistance at R126 per share. When it broke decisively above that level, that gave us the signal we needed. Immediately prior to the start of the war the oil price had been climbing, and in January 2026 there were riots in Iran which Trump and Netanyahu used as a pretext to begin the bombing. The price of Brent rose above $70 per barrel on 18th February, before the bombing started, and that triggered a rise in Sasol’s share price. We decided then that Sasol was probably under-valued and due for an upside move.
Sasol’s latest results for the year to 30th June 2026 show the benefits of the rising price of oil. Turnover was up 9% and earnings before interest taxation depreciation and amortisation (EBITDA) was up 17% while the company reduced its debt by 11%.
We do not normally advise investors to buy commodity shares like Sasol because they are riskier, but sometimes they can offer very good capital gains. In the case of Sasol the share appreciated rapidly after we added it to the WSL and then there was a correction as the oil price temporarily fell back in June and July this year. We held on because we thought there might be further upside potential.
The best investment policy is to try to hold onto your shares for at least three years, unless you are moving into a loss position (i.e. you had to execute an early stop-loss sale). This is because if you hold them for less than 3 years the Receiver may seek to declare you to be a share dealer – and then any gain you make will be added to your taxable income and you will be taxed on it at your marginal rate. If you hold for longer than 3 years, then your appreciation is treated as a capital gain for tax purposes and taxed at 18%.
As it turns out holding on to Sasol was the right decision and the share has now appreciated by 134% in about 8 months since we added it to the WSL – which is just shy of 200% per annum.