Market View
J200 105,226.00 +3.99% J203 113,286.00 +3.67% J210 113,994.00 +2.78% J211 128,677.00 +4.92% J212 26,783.00 +4.08% J213 144,492.00 +4.58%
Winning Shares (Top 5)
Code Name Added Price Latest % Gain % Gain/Year
SDO STADIO 2024-06-29 525 1479 +181.71% +77.21%
KRO KAROO 2024-11-27 76000 110000 +44.74% +23.06%
PPE PURPLE 2025-04-16 120 184 +53.33% +34.27%
GND GRINDROD 2025-08-23 1446 2788 +92.81% +77.16%
NED NEDBANK 2025-11-14 26163 30093 +15.02% +15.40%
Opinions (Top 5)
Code Name Date Action
ANG ANGGOLD 2026-11-06 View

06-11-2026 Anglogold Ashanti (ANG) is an international gold producer which used to have operations in South Africa (the last of which, Mponeng, has now been sold), and still has assets in the DRC, Tanzania, Ghana, Mali and the US. It had some significant problems in bringing the Obuasi mine into production and the problems with the Tanzanian government over royalties.

The company has 14 operational mines. Anglogold has retained its listing on the JSE despite having no South African assets. In its results for the year to 31st December 2025 the company reported that its cash flow had tripled to a record $2,9bn while gold production had increased by 16% and there was a 45% increase in the average gold price received.

The company said, "Adjusted EBITDA* was a record $6.3bn in 2025, while headline earnings(4) increased 186% year-on-year to $2.7bn for the year (from $1.0bn in 2024), reflecting higher realised gold prices, production growth and disciplined cost control. An interim dividend of $875m, or 173 US cents per share, was declared for Q4 2025.

The payout comprises 50% of free cash flow". In an update on the 3 months to 31st March 2026 the company reported gold production up 1% and a share buy-back program of up to $2bn. The company said, "EBITDA*(4) increased 130% year-on-year to $2.3bn in Q1 2026 (from $1.0bn in Q1 2025), while headline earnings(3) rose 187% to $1.3bn in Q1 2026, or 252 US cents per share (from $447m, or 88 US cents per share, in Q1 2025)".

In an update on the 3 months to 30th June 2026 the company reported free cash flow up 36% to $727m and headline earnings up 58% to $1bn. The company said, "Total cash costs per ounce* for the Group(1) rose to $1,480/oz in Q2 2026 from $1,226/oz in Q2 2025". In an update on the 3 months to 30th September 2026 the company reported gold production of 2,164m ounces and EBITDA up 12% with strong cash flows.

The company said, "Our Q3 2026 performance highlights AngloGold Ashanti’s structural quality and free cash flow* generation". Technically, the share has been rising since March 2024 in what looks like a volatile upward trend. This share remains a speculation on the gold price - which is strong at the moment.

On 2nd October 2026 the company was censured for not publishing its financial statements on time.

DTA DELTA 2026-11-06 View

06-11-2026   Delta Property (DLT) was a level 2 black empowered real estate investment trust (REIT) with a portfolio valued at R11,3bn and a loan-to-value ratio of 44,3%. Roughly 80% of its rental income was from the government or state-owned enterprises such as Eskom. The company specialised in renting buildings to government and quasi-government organisations in major South African cities.

During COVID-19 the company's exposure to government leases has turned out to be a benefit because those leases continued to be paid while commercial leases have come under extreme pressure. On 15th December 2020 trading in the share was suspended by the JSE. On 22nd April 2021 the company re-issued its financials with a 10% drop in the value of its portfolio of properties at end February 2020.

Its liabilities exceeded its assets by more than R4bn and its status as a going concern was in question. The JSE suspension was finally lifted on 30th July 2021 and it has been climbing strongly since then. In its results for the year to 28th February 2026 the company reported net profit up 221,9% and a loan-to-value (LTV) of 56,7%.

The company said, "For FY26, the Group delivered significantly improved financial results returning to profitability in a challenging operating environment". In a trading statement for the six months to 31st August 2026 the company estimated that distributable income per share would rise by between 20% and 30%.

Notably the share is still trading at a fraction of its NAV - which suggests that a takeover might be in the offing. In our view, this share remains a risky penny stock especially given the recent results. We think the loan-to-value (LTV) is still far too high. On 16th February 2024 the JSE censured Delta and gave it a R7,5m fine for accounting irregularities which might prevent the investing public from making sound investment decisions. 

GFI GFIELDS 2026-11-06 View

06-11-2026   Gold Fields (GFI) is a relatively high-cost international gold mining house with a single mine in South Africa - South Deep. South Deep was bought by Gold Fields in 2006 and it has struggled to make the mine profitable, pouring in a total of R32bn (R22bn purchase price plus R10bn in development costs) into it over the past 14 years.

Brett Kebble once described South Deep as, "The world's most expensive long drop...". South Deep is 3 kilometres deep and a very difficult mine with many technical complications, but it is the second largest unmined gold resource in the world - hence Gold Field's persistence. Gold Fields is working with an independent power producer (IPP) to build a 50MW project in SA.

The company has spent a total of $502m over the past two years to ensure that Damang and Gruyere (international operations) would produce 2 million ounces a year for the next ten years. South Deep now has R800m less in costs and R400m less in capital expenditure. The company is focusing on bringing the new Salares Norte gold mine in Chile into production.

On 11th July 2022 the company said that it would list on the Toronto Stock Exchange and that it would adopt a dividend policy of paying between 30% and 45% of profits out.  Its protracted investment in South Deep is definitely beginning to pay off with output expected to rise by about 25% over the next 4 years. On 12th August 2024 the company announced that it had acquired the remaining 50% of Osisko Mining for $1,57bn (R29bn).

In its results for the six months to 30th June 2026 the company reported attributable profit up 81% and headline earnings per share (HEPS) of 208c (US) compared with 115c in the previous period. The company said, "During the six months ended 30 June 2026, 61% of adjusted free cash flow(1) was paid to shareholders and the Company stepped up its share buy-back programme and completed share repurchases of US$300 million between March and July 2026".

In an operational update for the 3 months to 30th September 2026 the company reported gold-equivalent production of 605koz and all-in sustaining costs (AISC) of $1965 per ounce. The company said, "Additional share buy-backs of US$554 million were completed as at 3 November 2026, bringing total shares repurchased under the Additional Shareholder Returns Programme to US$854 million".

Technically, the share is volatile and subject to shifts in the international price of gold, but it has been in a strong upward trend over the past five years. It remains a volatile commodity play. It was added to the Winning Shares List (WSL) on 4th February 2025 at a price of 32915c.

It has subsequently risen to 60648c (5-11-26) after some profit taking.

OMN OMNIA 2026-11-06 View

06-11-2026 Omnia (OMN) is a diversified chemicals company supplying products to the agricultural, chemicals and mining industries in South Africa and 48 other countries. The Agricultural division is the leader in fertilizers in Southern Africa. It supplies granular, liquid and speciality fertilizers in Southern Africa, Eastern Africa, Australia, New Zealand, and Brazil.

The mining division is the leading supplier of explosives in South Africa, Mali, Swaziland, Sierra Leone, Malawi, Senegal, Zambia, Zimbabwe, Botswana, Mozambique, and the DRC. The chemicals division is a manufacturer and distributor of speciality, functional and effect chemicals and polymers operating throughout the African continent.

The company gets most of its sales from agriculture for fertilizers and the mining industry for explosives. In its efforts to diversify away from the South African economy, OMN acquired Oro Agri in America for $100m and Umongo Petroleum for R780m. They also commenced the construction of a R630m nitro phosphate plant at Sasolburg.

This company's performance reflects the general performance of the South African economy. It has been very well managed and grows consistently by acquisition and organically, but it is in very tough markets where it has become difficult to make good profits. It is a relatively risky investment and dependent on commodity prices and agriculture - but both of which have done well.

In its results for the year to 31st March 2026 the company reported revenue up 6% and headline earnings per share (HEPS) up 21%. The company said, "This was driven by strong volume and margin growth, supported by the strengthening competitiveness of our core businesses, with both Agriculture and Mining contributing robust earnings, margins and solid cash generation".

In a trading statement for the six months to 30th September 2026 the company estimated that HEPS would increase by between 18% and 28%. Technically, the share was in a downward trend from its peak in May 2022. We recommended waiting for it to break up through its long-term downward trendline, which happened on 18th June 2024 at 6087c and then the share was added to the Winning Shares List (WSL) on 12th January 2026 at 8207c.

The share has since moved up to 12280c (8-6-26). On the 14th of September 2026 the company announced that it had received a firm offer to buy all of its ordinary shares for R21,8bn or 13450c per share. The announcement caused the share price to jump up. Omnia shares are expected to be delisted from the JSE on 29th June 2027.

CMH CMH 2026-11-06 View

06-11-2026 Combined Motor Holdings (CMH) runs 43 car dealerships with 28 brands including Nissan, Volvo, Toyota, Opel, Subaru, Lexus, Mazda, Isuzu and Ford - selling both new and used vehicles. The motor industry is especially affected by the state of the economy because consumers can usually keep their vehicles on the road for longer in recessionary times.

The company is planning to cut its car rental staff by as much as one third, its fleet by 40% and 20 of its branches because of COVID-19. Electricity disruptions from Eskom and low business confidence have negatively impacted the business. In spite of this, the car hire business has been recovering steadily.

In its results for the six months to 31st August 2026 the company reported revenue up 6,6% and headline earnings per share (HEPS) up 18,6%. The company said, "Once again the Chinese brands made a significant impact, with their share rising from 14.8% to 20% of national sales. The Group has exposure to a number of the Chinese/ Asian brands, but with the proliferation of products and brands – and increasing each quarter, it is impossible to identify all the potential long-term winners".

We recommended waiting for a break up through its long-term downward trendline - which came at 1489c on 2nd February 2021. After that the share rose to 4000c before the impact of the Trump war in Iran took it back down to 3200c. It is now back in a rising trend and on an undemanding P:E of 6,9.

In our view, it represents good value at these levels. On 3rd November 2026 the company reported that its CEO, Jebb McIntosh, had passed away unexpectedly.

Winning Share: PPE
Opinion: CMH
Sasol and the Rising Oil Price  (2026-10-26)

Every major event that happens in the world inevitably offers some kind of investment opportunity for the private investor. The challenge is to work out how best to capitalise on it. So, it was with the war in Iran. At the time that the war began with the Israeli and American bombing raids on 28th…

Every major event that happens in the world inevitably offers some kind of investment opportunity for the private investor. The challenge is to work out how best to capitalise on it. So, it was with the war in Iran.

At the time that the war began with the Israeli and American bombing raids on 28th February 2026, we had already been watching the progress of Sasol for some time. The situation in Iran was tense with riots reported and North Sea Brent had climbed back up to $70 per barrel, but we had no idea that the Americans and Israelis were about to launch a bombing attack.

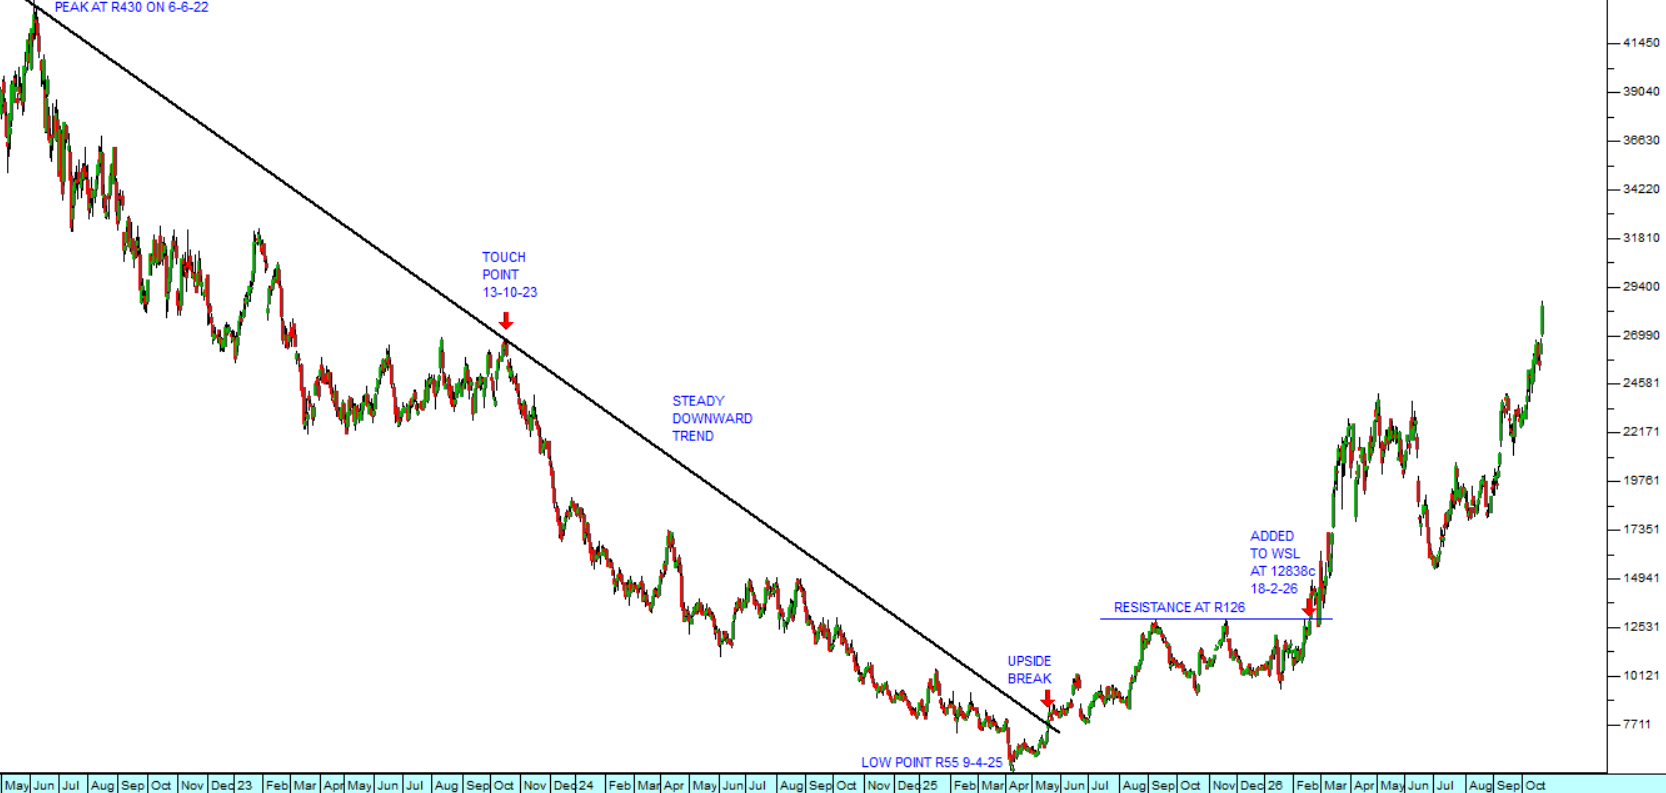
Sasol was always a blue-chip share and has historically occupied a dominant position in South Africa's synthetic fuels industry. It had, however been through some difficult times and the share price had fallen from a high of R430 per share to as low as R55 in April 2025. It then went through an extended period of sideways consolidation. We finally decided to add it to the Winning Shares List (WSL) on 18th February 2026 at a price of R128.36. Technically the share broke above resistance at R126 indicating that something was afoot. Consider the chart:

Sasol (SOL) : May 2022 - 23rd of October 2026. Chart by ShareFriend Pro.

The chart shows Sasol’s long downward trend that began in the middle of 2022, mainly because of the falling price of various grades of oil. North Sea Brent oil fell from a high of $125 per barrel on 8th March 2022 to its cycle low just below $60 per barrel in mid-December 2025. Since Sasol derives more than half of its revenues and profits from the fuel industry, it is directly linked to the price of oil.

Sasol had been recovering but had encountered significant resistance at R126 per share. When it broke decisively above that level, that gave us the signal we needed. Immediately prior to the start of the war the oil price had been climbing, and in January 2026 there were riots in Iran which Trump and Netanyahu used as a pretext to begin the bombing. The price of Brent rose above $70 per barrel on 18th February, before the bombing started, and that triggered a rise in Sasol’s share price. We decided then that Sasol was probably under-valued and due for an upside move.

Sasol’s latest results for the year to 30th June 2026 show the benefits of the rising price of oil. Turnover was up 9% and earnings before interest taxation depreciation and amortisation (EBITDA) was up 17% while the company reduced its debt by 11%.

We do not normally advise investors to buy commodity shares like Sasol because they are riskier, but sometimes they can offer very good capital gains. In the case of Sasol the share appreciated rapidly after we added it to the WSL and then there was a correction as the oil price temporarily fell back in June and July this year. We held on because we thought there might be further upside potential.

The best investment policy is to try to hold onto your shares for at least three years, unless you are moving into a loss position (i.e. you had to execute an early stop-loss sale). This is because if you hold them for less than 3 years the Receiver may seek to declare you to be a share dealer – and then any gain you make will be added to your taxable income and you will be taxed on it at your marginal rate. If you hold for longer than 3 years, then your appreciation is treated as a capital gain for tax purposes and taxed at 18%.

As it turns out holding on to Sasol was the right decision and the share has now appreciated by 134% in about 8 months since we added it to the WSL – which is just shy of 200% per annum.

October Month  (2026-10-19)

There are generally two types of risk in the share market – the risk that a specific share which you have bought falls known as unsystematic risk, and then the risk that the market as a whole falls and drags all your shares down with it - known as systematic risk. The systematic risk that the market…

There are generally two types of risk in the share market – the risk that a specific share which you have bought falls known as unsystematic risk, and then the risk that the market as a whole falls and drags all your shares down with it - known as systematic risk. The systematic risk that the market is in or about to enter a bear trend is obviously a vital consideration for the private investor. During a bear trend about 80% (or more) of shares will fall while only 20% will rise. This means that from a purely statistical point of view it is better for private investors to stay out of the market during bear trends.

It is also very important to be able to distinguish between a correction (which is often a buying opportunity) and a bear trend. The safest approach is always to always buy shares which are rising, in sectors which are rising in a market which is rising. At the same time keeping a strict stop-loss strategy is vital to protect the bulk of your capital. As a private investor you should have an absolute rule that you never lose more than 15% on any share market investment – ever – and that should include your dealing costs. This can only be achieved if you buy free-dealing shares and always adhere to a strict stop-loss strategy.

Today, Monday 19th October 2026 is the exact anniversary of the greatest single day crash in stock market history. Thirty nine years ago, on Monday 19th October 1987, Wall Street collapsed. The S&P500 index fell more than 20% in the day. Other famous bear trends have also begun in October month, including the infamous 1929 crash, the bear trend of the year 2000, the 2008 sub-prime crisis, and the bear trend of 2022 associated with the Ukraine War. So, October month has a bad reputation with investors, and they generally heave a sigh of relief when it is over.

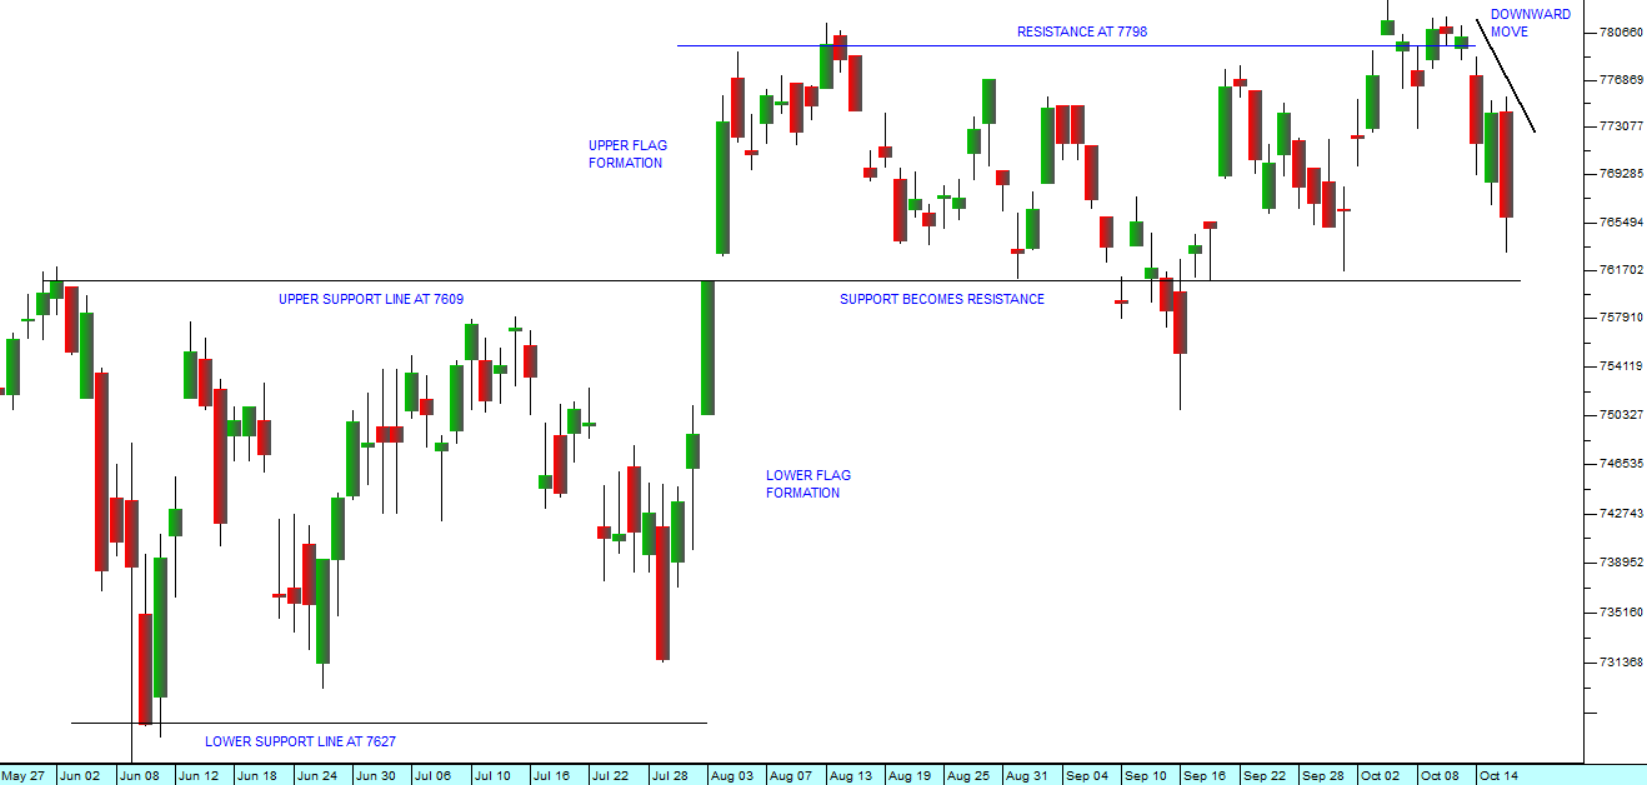
Ominously, Wall Street has been falling over the last week as the Iran war flared up again, pushing the price of North Sea Brent up to nearly $110 per barrel. Consider the chart:

S&P500 Index : 27th of March 2026 - 16th of October 2026. Chart by ShareFriend Pro.

In our analysis, we have drawn your attention to the fact that the S&P500 index has been moving through two sideways markets or flags as the countervailing forces of the rising oil price and the profitability of the artificial intelligence (AI) revolution play out.

The climb in the fuel price is causing a re-evaluation of inflationary risks throughout the world, but especially in America, where the price of petrol has remained stubbornly above $4 per gallon and diesel has hovered above $6 per gallon. With the mid-term elections just weeks away, Republicans and especially Trump are facing a barrage of criticism for their handling of the economy. The Iranians on the other hand are doing everything in their power to keep the oil price at high levels to put the maximum pressure on Trump.

What is notable is that the high oil price appears to be having less and less impact on Wall Street as time goes by. When Trump and Netanyahu began their war with Iran the S&P fell back sharply to 6611 on the 6th of April 2026, and the price of Brent oil went above $110 per barrel. Today Brent is again hovering close to those levels and the S&P has recently managed to reach a new record high at 7818. The world has been facing increased levels of inflation, rising interest rates, and record bond yields - but despite that, AI and corporate profits continue to take the market higher.  

In our opinion, as soon as October month is safely behind us and especially if the mid-term elections have the effect of reducing Trump to a lame dog president, we can look forward to a Christmas rally in the S&P500 during the festive season and into next year. As usual, we strongly advise you to be vigilant and to maintain your stops.

Quantum Computing  (2026-10-12)

We live in an age where advances in technology are driving the gains in productivity and profits, and then being discounted directly into share prices. Artificial intelligence (AI) is already well established and being used by most companies to improve productivity. This can be seen in the results…

We live in an age where advances in technology are driving the gains in productivity and profits, and then being discounted directly into share prices. Artificial intelligence (AI) is already well established and being used by most companies to improve productivity. This can be seen in the results coming out of the companies in the S&P500 index. The impact of AI has only just begun to be discounted and now the next major technological breakthrough, quantum computing, is hovering in the background.

Quantum computing is essentially a jump forward in hardware which allows computers to analyse multiple different solutions simultaneously. Instead of using bits which are either 1 or 0, a quantum computer uses qubits which can exist in multiple states simultaneously - together with quantum entanglement. The technology uses the laws of physics at the atomic and subatomic level to solve complex problems much faster than regular computers, even supercomputers. Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are rushing to install quantum computing into their infrastructure. In a word, quantum computing will increase the power of AI substantially making it even faster and more powerful than it already is.

With that background, the earnings of S&P companies for the third quarter are beginning to trickle in, with 19 companies having reported so far. Total 3rd quarter earnings for those companies that have reported results already are up +150.9% from the same period last year on the back of revenues which are +27% higher. 79% of those companies are beating EPS estimates and 73.7% are beating revenue estimates.

The average estimate for all S&P500 companies is that earnings will be up by 24,3% in the 3rd quarter when compared with a year ago – and this will be the 8th straight quarter where estimates have been in positive double digits. 15 out of 16 sectors are expected to make significant gains – led by the technology and energy sectors.

As things stand now, the progress of the S&P500 index is being significantly held back by developments in Trump’s Middle East war and the price of oil. Iran would like to hold the price of North Sea Brent above $100 per barrel, at least until after the mid-term elections on 3rd November 2026 – which of course is very bad news for the struggling Republican party and Trump.

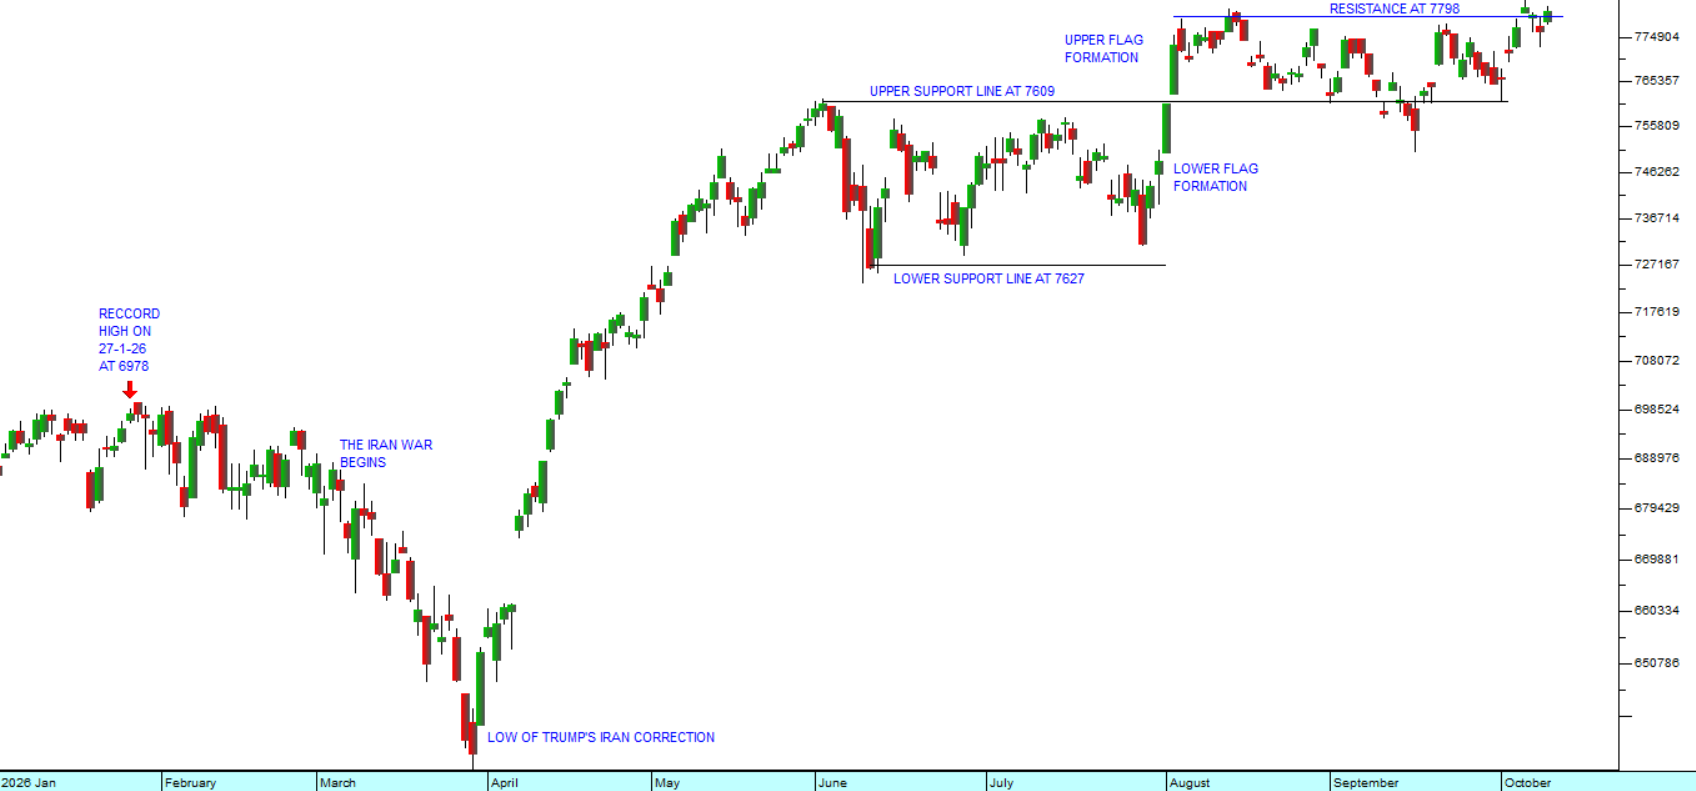
Looking at the chart, the S&P500 index has been moving through a series of protracted sideways markets for the past four months. During that time, technology and the prospects of that technology have not stood still. They have been advancing at a rapid pace.

Our belief is that as soon as the situation in the Middle East is resolved and the oil price comes back to where it was before the war began, the S&P will suddenly begin discounting the impact of the accumulated technical advances and move sharply higher. It will be like removing the lid from a pressure cooker. Consider the chart:

S&P500 Index : January 2026 - 9th of October 2026. Chart by ShareFriend Pro.

So, what we are saying is that considerable bullish potential has been built up by this war and its impact on oil prices. This can be seen from the fact that even with Brent at over $100 a barrel now, the S&P is still making new record highs, based on the exceptional estimates of 3rd quarter earnings and beyond.

There are, of course, those who believe that Brent is about to go much higher – like to $125 per barrel - given the escalation in Yemen with the Houthis and the attacks on the Saudi pipeline. But in our view the underlying direction of the oil price must be downwards as the world moves away from fossil fuels and towards renewables, especially solar.

To be safe, ensure that you have a strict stop-loss level for all the shares in your portfolio. That is the ultimate protection against unexpected downtrends and bear markets. Your absolute rule should be to never lose more than 15% on any share market investment ever – including your dealing costs. Sometimes it is difficult to achieve this, but provided you always choose shares which are free-dealing, it simply becomes a matter of self-discipline. And then if you are able to make several hundred percent on your winners, mathematically, you must be successful over time.


JSE Top 40

105,226.00 (+3.99%)

All Share

113,286.00 (+3.67%)

Financial 15

26,783.00 (+4.08%)

J200
J203
J212
Top Gainers
# Code Name Close (c) % move
1 MHB MAHUBE 861 +43.02%
2 MKR MNTKRENEW 4351 +22.29%
3 CCC CILOCYBIN 90 +15.38%
Top Losers
# Code Name Close (c) % move
1 CHP CHOPPIES 75 -11.76%
2 ISO ASPI 2900 -11.59%
3 SEP SEPHAKU 201 -8.64%

Top Movers – Charts

Top Gainer: MHB
Top Loser: CHP