Market View
J200 105,986.00 -0.48% J203 113,551.00 -0.41% J210 130,233.00 +0.15% J211 119,389.00 -1.21% J212 25,642.00 -0.55% J213 136,140.00 -0.91%
Winning Shares (Top 5)
Code Name Added Price Latest % Gain % Gain/Year
ADR ADCORP 2025-05-20 550 628 +14.18% +10.69%
KAP KAP 2026-04-30 240 269 +12.08% +31.73%
MRF MERAFE 2026-06-02 128 136 +6.25% +21.52%
VOD VODACOM 2025-02-04 11611 15421 +32.81% +20.33%
VKE VUKILE 2023-12-07 1410 2355 +67.02% +24.13%
Opinions (Top 5)
Code Name Date Action
EPE ETHOSCAP 2026-09-17 View

17-09-2026   Ethos Capital Partners (EPE) is a private equity fund (PEF), incorporated in Mauritius, which invests into unlisted companies for long-term capital appreciation on behalf of its investors. Like most investment holding companies, Ethos trades at a significant discount to its net asset value (NAV).

Fifty-six percent of their assets are in South Africa and 39% in the rest of Africa. It has stakes in Tymebank, Ster Kinekor and Brait. The risk in this company appears to be minimal since it does not invest a significant proportion of its funds in any one investment and its investments have performed well in the circumstances.

It does not pay dividends, so the investor has to look for a capital gain. In its results for the six months to 31st December 2025 the company reported net asset value (NAV) up 0,5% at 792c per share. The company said, "Return of capital to shareholders - From listing to 30 June 2025: - R243 million returned via share buybacks and the unbundling of Brait ordinary shares ("Brait Shares") - During the period ended 31 December 2025: - Unbundling of Brait Bonds on 8 December 2025 which resulted in the return of R171 million to shareholders".

In a trading statement for the year to 30th June 2026 the company estimated that its NAV would fall by between 33% and 37%. EPE is well-traded with an average of over R720 000 worth of shares changing hands on average every day. The share has been falling since its high in November 2025, but it may now have found support at around 450c.

In our opinion this share, although volatile, should turn out to be a good investment at current levels - depending on the progress of the current trend in world markets. The separate and successful listing of Optasia on 4th November 2025 resulted in short-lived a jump in the share price. 

PAN PAN-AF 2026-09-17 View

17-09-2026   Pan African Resources (PAN) is a London- and JSE-listed re-treatment gold producer. With its Elikhulu plant it will be able to produce about 700 000 ounces of gold a year at a cost of about R450 564 per kilogram against a current gold price of close to R1m. This means that over its life it will produce revenue of approximately R15bn of which R5,3bn will go back into the economy in the form of mine expenses, creating a highly profitable entity with minimal risks.

It will also employ 350 people. The company has approved the construction of a 10mw solar power plant. On 4th June 2024 the company announced that it signed a five-year wage deal with the National Union of Mineworkers (NUM) for an increase of 5,3% per annum over the period. In its results for the year to 30th June 2026 the company reported gold production up 38,6% and revenue up 114,2%.

Headline earnings per share (HEPS) increased by 199.5% and all-in sustaining costs were $1867 per ounce. The company said, "The Group is degeared and in a net cash position (FY25: net debt of US$150.5 million), with the only outstanding debt being the domestic medium-term notes (DMTNs) of US$49.7 million". Technically, the share has been in a strong upward trend since its low of 288c in June 2023 and we added it to the Winning Shares List (WSL) on 31st January 2024 at 430c.

It has since risen to a high of 3881c on 2nd March 2026 before falling back as the gold price came off. We see this as a good operation, but potentially volatile - which means risk. We would advise investors to be cautious, but with the gold price having broken convincingly once above resistance at $5000 and likely to return there in due course, it has been an excellent speculation.

On 22nd June 2026 the company announced that its shares were listed on the Australian Stock Exchange (ASX).

SRI REIT 2026-09-17 View

17-09-2026   Supermarket Income is a real estate investment trust (REIT) which focuses on investing in supermarket real estate in the UK and Europe. It has a portfolio worth GBP1,8bn with tenants such as Tesco, Waitrose and Sainsbury. In its results for the year to 30th June 2026 the company reported occupancy and rent collections at 100% with a loan-to-value (LTV) of 43,9%.

The company said, "During the year, SUPR completed £454 million of acquisitions, and a further £222 million post year end, having successfully deployed the proceeds of the July 2026 equity raise". The share listed on the JSE on 18th December 2024 and has been moving sideways since then.

This should be a solid, rand-hedge investment dependent on the progress of the UK and European economies. We don’t like its high LTV ratio.

ATT ATTACQ 2026-09-16 View

16-09-2026   Attacq (ATT) is a BEE level 2 property developer that converted to a real estate investment trust (REIT) in May 2018 and has been listed on the JSE since 2013. It is the owner of the Mall of Africa in Halfway House and the developer of the Waterfall City complex. It is now building the Ellipse Waterfall residential high-rise, which will have 590 apartments priced between R1,5m and R12m.

Overall, Waterfall City is expected to consist of over 1 million square meters of multi-use space over the next 5 to 10 years. In its results for the year to 30th June 2026 the company reported distributable income per share up 15,5% and loan-to-value (LTV) at 25%. The company said, "Installed photovoltaic (PV) systems and water backup: 18.5MWp installed PV systems, generating 13.7% of total energy consumed and 5.3Ml of backup water capacity added (FY25: installed 16.6MWp, 9.1% energy mix)". The share was added to the Winning Shares List on 25th January 2024 at a price 964c.

It has since moved up to  1715c (23-6-26). We expect it to continue to perform well despite some profit taking over the Iran war. On 25th November 2025 Business Day reported that Attacq had sold 60% of its residential development project in Waterfall City off plan. 

PMR PREMIER 2026-09-16 View

16-09-2026   Premier is a food producer which was spun out of Brait (BAT) through an initial public offer (IPO) and separately listed on 24th March 2023 which raised R3,6bn at a share price of 5382c per share. Brait retained 47,1% of Premier. Premier has managed to mitigate the impact of loadshedding on its operations, the costs of which were not a material impact on its financial performance.

In its results for the year to 31st March 2026 the company reported revenue up 6,6% and headline earnings per share (HEPS) up 27,7%. The company said, "Significant deflation in maize input prices, from the previously elevated levels in FY2025, was experienced during the year with the white maize spot price declining 31% since March 2025".

In a trading statement for the six months to 30th September 2026 the company estimated that HEPS would increase by between 22% and 32%. We expect this share to be a blue chip quality operation which is sought after by institutional investors - and hence a solid, if unexciting investment for private investors.

We added it to the Winning Shares List (WSL) on 21st August 2024 at 7635c. It subsequently moved up to a peak of 19693c on 30th June 2026 and has been correcting since then. We expect it to continue to perform well in due course. 

Winning Share: KAP
Opinion: ATT
Muddy Waters  (2026-09-14)

It has become difficult to keep up with all the news coming out of America. Trump’s erratic behaviour is combining with other factors to make the systematic risk picture complicated and unpredictable. On the one hand, there have been some excellent results coming out of the S&P500 companies riding…

It has become difficult to keep up with all the news coming out of America. Trump’s erratic behaviour is combining with other factors to make the systematic risk picture complicated and unpredictable. On the one hand, there have been some excellent results coming out of the S&P500 companies riding the wave of AI.

AI Boom Lifts S&P 500 Earnings 32% as 86% of Companies Beat Estimates | Business | CryptoRank.io

Wall Street investors now expect that the earnings of the S&P500 companies will be roughly 32% higher than they were a year ago as second quarter earnings dramatically exceed analysts’ expectations. 86% of S&P500 companies have now reported earnings above forecast. Alphabet reported second-quarter earnings that included a $98 billion gain, while Amazon recorded $53.4 billion in non-operating pre-tax income, primarily related to its Anthropic investments. Nvidia’s revenue in the second quarter was $96,2bn – more than double the same quarter last year.  

On the negative side, the price of North Sea Brent oil spiked up to nearly $110 per barrel last week, but has now fallen back to just below $100. This decline to $100 comes because of new hopes for peace negotiations such as planned meetings between Gulf and Iranian foreign ministers. These hopes helped ease immediate fears of a total, prolonged blockage of the Strait of Hormuz. At the same time, oil producers in the Persian Gulf shifted shipments to alternative pipeline capacities and non-Middle Eastern regions (like the US, Canada, and Ghana) which increased output to bridge supply gaps. Finally, major international bodies, including the International Energy Agency indicated that there was slowing consumption and a broader economic slowdown, and notably reduced oil demand from major importers like China driven partly by the transition to electric vehicles.

In the middle of all this, on Tuesday and Wednesday this week the US Federal Reserve Bank’s monetary policy committee will be meeting to decide on the future course of interest rates, and they will be focusing on these figures.

https://coinpaper.com/35641/stock-market-today-sp-500-nasdaq-jump-1-as-oil-falls-despite-hot-cpi

The US inflation rate for August 2026 came in at 3,4% for the year to the 31st August 2026. This was the same rate as July and shows broad increases across both goods and services with the price of gasoline being the major contributor. In the month itself, inflation was 0,4% because of a 3,9% increase in the price of gasoline.

Following hotter-than-expected August inflation data, market metrics and prediction venues show a massive shift toward monetary tightening. The CME Fedwatch Tool suggests that the probability of a 25 basis point hike in  interest rates is now between 84% and 87% while Polymarket says there is an 81% probability. A hike in interest rates will add to the misery of consumers in America already facing an average price across the country of $4.30 per gallon of petrol.

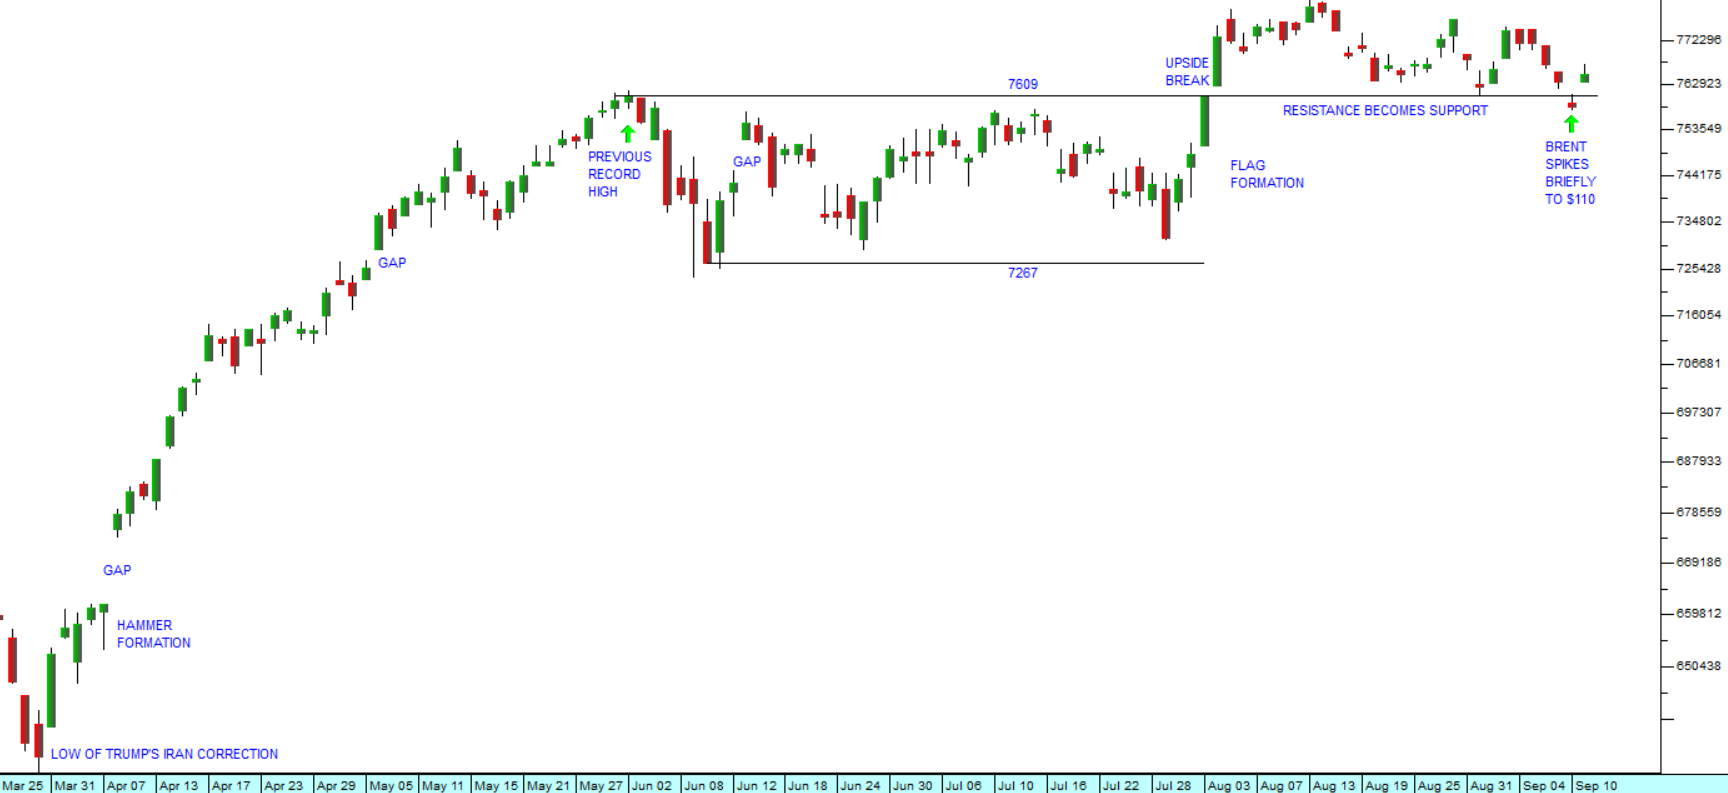
The S&P500 index has been trying to discount all these disparate forces and is basically moving sideways since it broke above the key support/resistance level at 7609. Consider the chart:

S&P500 Index : 25th March 2026 - 11th of September 2026. Chart by ShareFriend Pro.

There can be little doubt about the bullish sentiment which underlies the extended sideways market in the S&P. The news coming from big tech companies appears to be slowly overcoming the bad news coming out of the Middle East. The unexpected spike in the oil price to $110 was short-lived, but it did unnerve the market for a day. That was quickly rectified the next day.

And in the background is the looming mid-term election in America, which is increasingly focusing the Trump camp’s attention, resulting in some radical moves on his part like promising to pay every adult American $5000 if the Republicans win both the House and the Senate. The cost of this is a further $1,23 trillion to be added to the budget deficit already above $40 trillion. He also said that after the elections the petrol price will drop back to $2 per gallon – and anyone who believes that is not following what is happening on the ground.

Trump approval rating hits new low over Labor Day weekend

The Focaldata/Financial Times poll released on September 6, 2026, found that only 32% of Americans now approve of Trump's job performance. Trump's approval rating dropped three points from the previous month, the lowest since the poll series began in May. Critically, his approval among Republicans fell to 72%, a two‑point decline and a new low for that group. The poll was conducted from August 28 to September 2 with 2,178 U.S. adults surveyed. Only 17% of respondents approved of Trump's handling of inflation and the cost of living, while 69% disapproved.

In our view, the Republicans will almost certainly lose the House and the Senate race is now a “toss-up”. If he loses both, we can expect impeachment proceedings to commence promptly.

The S&P500 and markets around the world will ultimately be drawn higher by the AI driven boom in American and elsewhere. We expect new record highs on all indexes in due course.

The Currency  (2026-09-07)

Perhaps the best way to measure the progress of South Africa as a country is to look at our currency – especially against the so-called hard currencies of the Western World. Its strength or weakness gives a very good overall picture of how the country is doing economically, politically and in terms…

Perhaps the best way to measure the progress of South Africa as a country is to look at our currency – especially against the so-called hard currencies of the Western World. Its strength or weakness gives a very good overall picture of how the country is doing economically, politically and in terms of its image with overseas investors.

As an emerging economy, South Africa is not regarded as a poor country, but rather as one which is striving to become first world. For overseas investors this typically means a country and a currency which offers high risk and high potential return. Whereas a 10-year US Treasury Bill can offer the international investor a return of 4,8%, a South African 10-year government bond offers around 8,8% - that is 4% better, if the investor is prepared to take the risk of investing here.

We have a number of advantages over other emerging markets. Perhaps most importantly, we have relatively low inflation. In fact, due to the tireless efforts of Lesetja Kganyago, Governor of the Reserve Bank, our inflation rate is very comparable to many First World countries – and certainly far better than many of the other emerging economies. For example, Turkey’s inflation rate is 31,5%, Argentina is at 33,8% Egypt is at 14,9% and Columbia is at 6%.

We are generally grouped among those less risky emerging economies with lower inflation rates like Brazil (4,6%), India (4,4%), Mexico (3,4%), Indonesia (2,9%), and South Korea (2,8%). These are very comparable to the inflation rates of First World economies like Europe (3,3%), the United Kingdom (2,9%) and America (3,4%).

Approximately $19bn worth of rands are traded in our currency market every day on average. This makes it a highly liquid and very free currency exchange. Overseas investors can quickly take or sell large positions in what is a strong and well-organised market. This has tended to mean that the rand has become a proxy for all emerging economies. When international sentiment is risk-on they pile into our currency and government bonds. When it is risk-off, as it was when Trump began his war with Iran, they sell out quickly.

But overall, for at least the past 17 months the rand has been steadily appreciating against most first world currencies. In our view, this is related to the stabilising impact of the government of national unity (GNU) and the fact that the ANC is no longer in complete control. This together with the various initiatives set in motion by President Ramaphosa have meant that the economic environment has been steadily improving since April 2025.

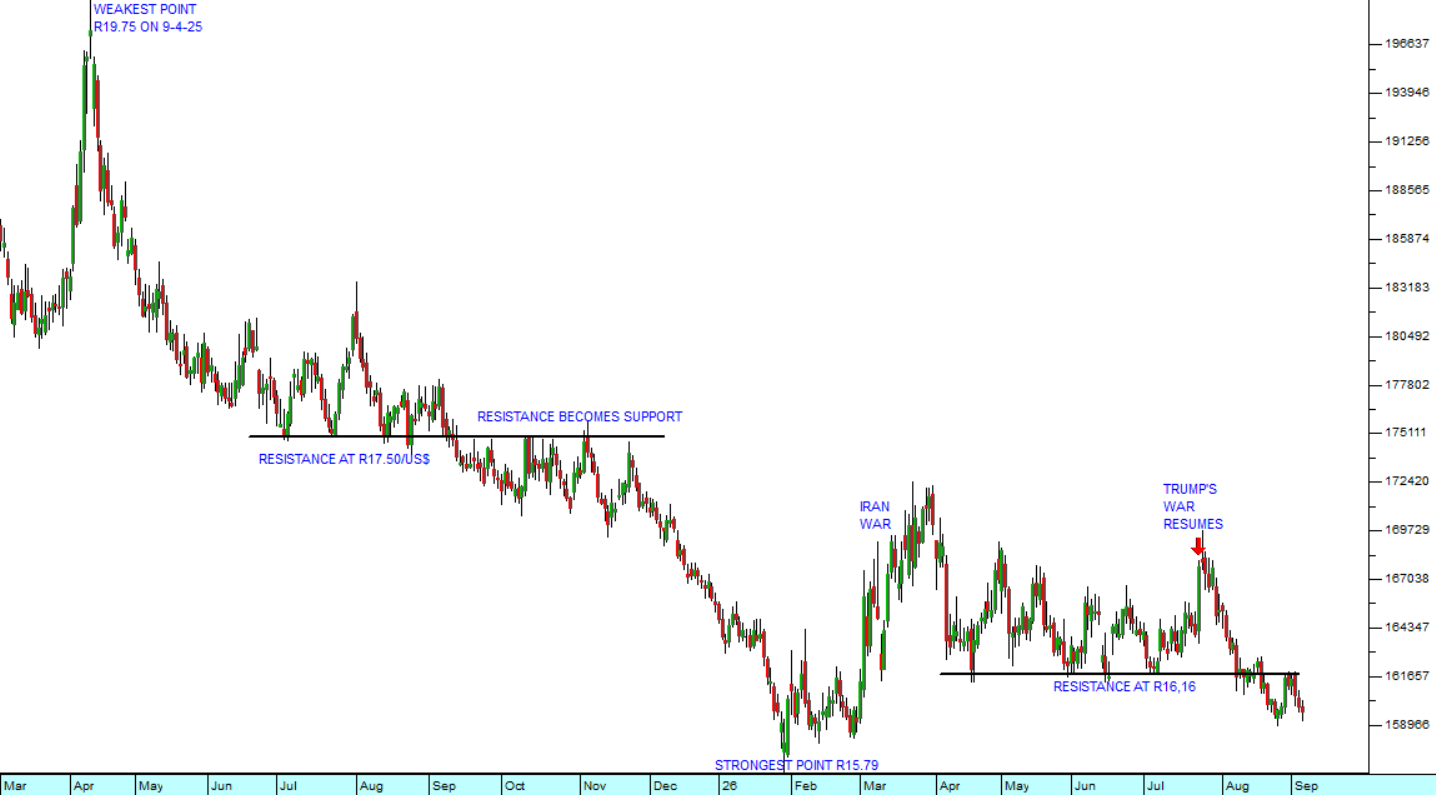
On 10th April 2025 one euro would have cost you R21,90 and today it costs R18,53. On the same day, one British pound would have cost you R25,34 whereas today it costs only R21,56 and of course over the same time period the US dollar has fallen from being worth R19,75 to being worth R15,96. Consider the chart:

South African rand/US dollar : March 2025 - 4th of September 2026. Chart by ShareFriend Pro.

What is significant about this chart is that it clearly shows the steady improvement in international sentiment towards South Africa. The massive, well-informed international investors of the world are betting on our country and putting their money here instead of elsewhere. That is a significant vote of confidence and one which many South Africans caught up in the cut and thrust of daily life here do not appreciate.

In our view, the rand is about to break below its previous cycle low of R15.79 to the US$ made on 29th January 2026. The outcome of the municipal elections on 3rd November 2026 will have a significant impact. If the ANC loses further ground and the DA gains ground (which is what we believe will happen) then you can expect the rand to appreciate further.

A stronger rand is good for everyone in South Africa. It means lower fuel prices, lower inflation, lower interest rates, more stability and a better future for everyone involved in the economy. It is the most telling and reliable indicator of our progress as a nation.

Harmony Takes Off  (2026-08-24)

The gold price has been in a persistent correction since its record high on 28th January 2026. It has been in what technical analysts call a descending flag formation which we have drawn you attention to on several occasions. As with any formation we are looking for the direction of the breakout…

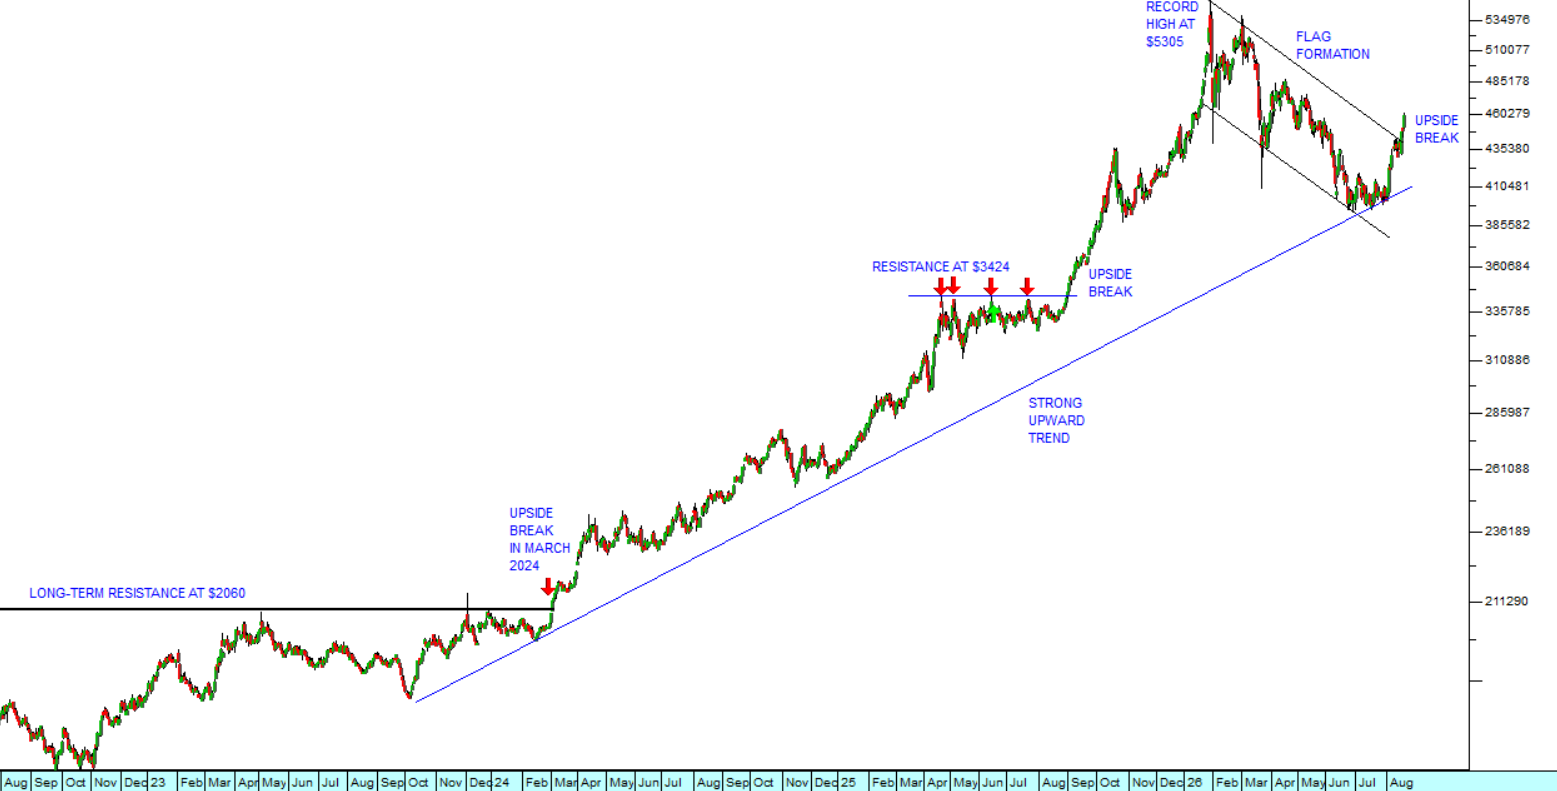
The gold price has been in a persistent correction since its record high on 28th January 2026. It has been in what technical analysts call a descending flag formation which we have drawn you attention to on several occasions. As with any formation we are looking for the direction of the breakout from that formation to give a clear idea of the future trend. In the case of gold, we have always been confident that it would break to the upside – and that is what it did last week on 19th August 2026. Consider the chart:

Gold price in US dollars : August 2022 - 21st Of August 2026. Chart by ShareFriend Pro.

The chart shows the US dollar price of gold since August 2022. It broke up out of a long-term sideways pattern in March 2024, and we drew your attention to that in the Confidential Report at the time. The chart shows how the upward trend was paused in 2025 until the precious metal broke above resistance at $3424 and it shows the all-time record high of $5305 on 28th January 2026.

The flag formation has taken place between two parallel downward sloping trendlines, showing how gold lost about $1000 over 5 months then found support before breaking to the upside.

As a private investor you should be thinking about which shares would have enabled you to capitalise on gold’s amazing run – and one of the best was Harmony. Of course, gold shares are always going to be speculative and risky, but under the right circumstances they can provide an excellent long-term investment.

In the case of Harmony, the key, for us, was its purchase of the Mponeng gold mine for $200m in September 2020. This was a very brave, potentially dangerous acquisition and we waited for some time before recognising that they were making a success of it. Mponeng is the deepest mine in the world. It is currently mining at depths of around 3800 meters with plans to go deeper to 4200 meters. This means that it is operating 2 kilometres below sea level from the Highveld near Carletonville. At those depths the grade is excellent - around 11,27 grams per ton – more than double the average grade for South African gold mines. The problem is that mining at those extreme depths is expensive and potentially very dangerous. It is the very definition of a high-risk, high-return investment.

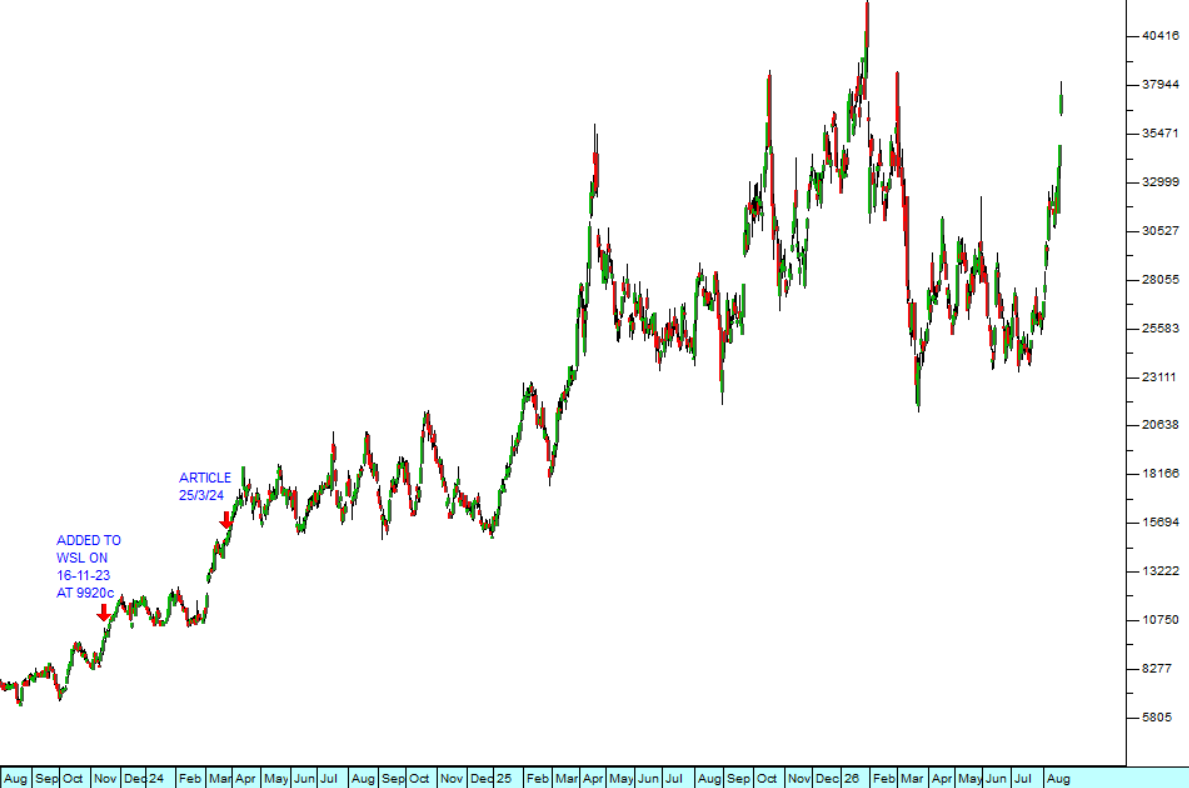
We added Harmony to the Winning Shares List (WSL) on 16th November 2023 at a price of 9920c per share. It reached an all-time high of 40841c on 28th January this year before falling back as gold corrected. Since 3rd August 2026 it has been moving up strongly again as gold recovered. Consider the chart:

Harmony (HAR) : August 2023 - 21st of August 2026. Chart by ShareFriend Pro.

Harmony published an excellent trading statement on Friday last week, predicting that its headline earnings per share (HEPS) would increase by between 90% and 105% in US dollars. 

Altogether, Harmony has risen by more than 250% since we added it to the WSL nearly 3 years ago and we believe it will continue to perform well – but it remains a commodity share and hence both volatile and risky.

JSE Top 40

105,986.00 (-0.48%)

All Share

113,551.00 (-0.41%)

Financial 15

25,642.00 (-0.55%)

J200
J203
J212
Top Gainers
# Code Name Close (c) % move
1 EUZ EUROMET 210 +740.00%
2 RHB RHBOPHELO 180 +46.34%
3 APF ACCPROP 41 +17.14%
Top Losers
# Code Name Close (c) % move
1 BWN BALWIN 1 -99.77%
2 BAC AFBITCOIN 352 -30.98%
3 GML GEMFIELDS 64 -13.51%

Top Movers – Charts

Top Gainer: EUZ
Top Loser: BWN