Market View
J200 104,981.00 -0.55% J203 112,895.00 -0.49% J210 113,784.00 -1.74% J211 127,641.00 -0.31% J212 26,813.00 +0.37% J213 144,096.00 +0.06%
Winning Shares (Top 5)
Code Name Added Price Latest % Gain % Gain/Year
ABG ABSAGROUP 2025-10-11 19460 23294 +19.70% +18.11%
WVR WEAVER 2025-08-23 4399 4700 +6.84% +5.60%
BLU BLUETEL 2025-01-23 610 874 +43.28% +24.01%
ATT ATTACQ 2024-01-25 965 1779 +84.35% +30.13%
RDF REDEFINE 2025-07-18 480 656 +36.67% +27.77%
Opinions (Top 5)
Code Name Date Action
GRSP GOLDRUSH 2026-11-13 View

13-11-2026   Previously, RECM Calibre, Goldrush is a company engaged in Bingo, Limited Payout Machines, and Retail Sports Betting. In its results for the six months to 30th September 2025 the company reported gaming revenue up 4% and headline earnings per share (HEPS) of 7,13c compared with 113,8c in the previous period.

The company said, "Food and beverage revenue, which is only associated with Bingo premises, increased by 10% to R37.5m from R34.2m. Total Income for the six months reached the R1bn level for the first time and was up 5% on the corresponding reporting period." Goldrush owns 50% of Sizekhaya which has just been awarded the lucrative R90bn contract to run the national lottery.

Business Day reported on 24th June 2025  that the awarding of this contract may be controversial as members of the National Lottery Commission (NLC) have links to the adjudication committee which decided the winner indicating a conflict of intereSt. In a trading statement for the six months to 30th September 2026 the company estimated that HEPS would be between 35c and 36,4c compared with 7,13c in the previous period.

The company said, "The difference between the LPS and the HEPS numbers reflects an impairment of Goodwill and Intangible Assets". Since the listing of Goldrush, the volume traded has dropped off substantially to an average of R28 000 per day on average. The share price has also fallen back to 620c (12-11-26) which indicates that there is considerable selling.

It is early days, but we believe that this share may be dangerous for private investors.

ENX ENXGROUP 2026-11-13 View

13-11-2026 The enX Group (ENX) is a "...diversified industrial group that provides branded products and services to the petrochemical, fleet management, logistics and industrial sectors." It includes Austro which distributes wood-working equipment and tooling. Finally, it includes New Way Power which manufactures, installs, and maintains diesel generators.

Its fleet division engages in fleet management and logistics as well as vehicle tracking. Then ENX Petrochemicals produces and markets oil lubricants, plastics polymers, rubber, and speciality chemicals in Southern Africa". It disposed of the EIE group with effect from 1st April 2022.  On 15th July 2019, the company announced that it had sold Eqstra, a fleet management company, to Bidvest for R3,1bn.

On 15th April 2021, the company announced that it had sold its British fork-lift and container business for GBP31m. The proceeds will be used to pay down debt. This is clearly a company that will benefit directly from any improvement in the South African economy, but which is making acquisitions both locally and, in the UK, to ensure growth, no matter what happens.

On 4th April 2022, the company announced a special dividend of 200c per share as a result of the sale of its subsidiary, EIE. In its results for the year to 31st August 2026 the company reported a headline loss of 12,3c per share compared with a loss of 9,7c in the previous period.

The company said, "Revenue from continuing operations amounted to R105 million (2025: R143 million)". Technically, the share has been moving down since July 2024. We advise waiting for it to establish a new upward trend before investigating further.

LHC LIFEHC 2026-11-13 View

13-11-2026 Life Healthcare (LHC) is the second-largest, JSE main-board listed, healthcare company with private hospitals, same-day clinics and surgeries and healthcare companies in South Africa, the UK (Alliance Medical) and Western Europe. The out-going CEO, Shrey Viranna, says that the group is trying to diversify away from conventional hospitals more towards day-clinics and non-acute services.

It is also trying to diversify away from medical aid schemes towards people who pay for their medical attention out of their own pockets. They have launched MyLife Clinic which offers a consultation and basic medication for R300. In its results for the six months to 31st March 2026 the company reported revenue up 2,4% and headline earnings per share (HEPS) of 55,1c compared with a loss of 155,8c in the previous period.

The company said, "The Group is in a strong financial position as at 31 March 2026, with net debt to normalised EBITDA (as per bank covenant definitions) of 0.93 times". In a trading update for the 11 months to 31st August 2026 the company reported revenue growth of 1,7% and paid patient days (PPD) up by 0,8%.

The company said, "Normalised EBITDA(2) for the review period increased by c. 5.7%, reflecting progress against the Group’s multi-year cost-saving programme and ongoing operational efficiencies". In a trading statement for the year to 30th September 2026 the company estimated that HEPS would increase by between 8% and 13%.

The company said, "The disposal of LMI in the prior year resulted in a R2.4 billion net gain" which impacted HEPS. Technically, the share peaked at 4700c in September 2014 and then entered a long downward trend. It is now trading for around 1245c (13-11-26). It has not yet broken up convincingly through its long-term downward trendline.

In our view, this share looks like reasonable value at current levels but investors should wait for the price to break strongly up through the downward trendline before investigating further. 

SSU SSU 2026-11-13 View

13-11-2026 Previously called Tsogo Sun Hotels, Southern Sun Hotels is a gaming, hotel and entertainment business which has split into separate gaming and hotel businesses in order to unlock shareholder value and to enable each business to become much more focused. As President Ramaphosa stabilises the economy, following the pandemic and introduces more growth-oriented policies we can expect business and consumer confidence to gradually recover.

The company's investment in limited payout machines (LPM) and electronic bingo terminals (EBT) has proved to be profitable. These are located mainly in restaurants and bars and outperform larger gambling outlets, but they are impacted by COVID-19. In its results for the six months to 30th September 2026 the company reported revenue up 12% and overall occupancy of 61,8%.

Headline earnings per share (HEPS) is expected to increase by between 35% and 44%. We have been saying for some time that this share looked oversold to us. Since COVID-19 the share went through an extended island formation. We advised waiting for a clear upside break through the share's downward trendline.

That break came on 21st March 2021 at 175c per share. Since then the share has risen rapidly to current levels around 1087c (12-11-26). It was added to the Winning Shares List (WSL) on 17th May 2024 at 555c.

UPL UPARTNERS 2026-11-12 View

12-11-2026   Universal Partners (UPL) is an investment holding company with a primary listing in Mauritius and a secondary listing on the Alt-X of the JSE. It listed in 2013 and has made five investments: (1) Dentex Healthcare Group, which owns 56 dental practices in the UK; (2) Yasa, a distributor of controllers for high power density electric motors.

This company was sold to Mercedes Benz for GBP42,8m. (3) SC Lowy, a market-maker in distressed and high-yield debt especially in Asia; (4) Propelair, a supplier of water-efficient toilets in the UK; (5) JSA Services, a provider of personal service companies, payroll and umbrella services to temporary workers in the UK.

In its results for the year to 30th June 2026 the company reported net asset value of 1158 pence per share compared with 1176 pence in the previous period. The company made a headline loss of 1,835 pence per share compared with a loss of 11,545 pence in the previous period. The company said, "The Company has made six investments since listing and successfully concluded two exits".

In an update on the 3 months to 30th September 2026 the company reported a loss of 17,9 pence per share. This share is far too thinly traded to be of interest to private investors.

Winning Share: WVR
Opinion: GRSP
Democrat Sweep  (2026-11-09)

It seems fair to say that while most analysts and investors expected the Democrats to do well in the US mid-term elections, most were also caught completely off-guard by the extraordinary extent and depth of that win - and this has resulted in a burst of increased volatility in the markets as they…

It seems fair to say that while most analysts and investors expected the Democrats to do well in the US mid-term elections, most were also caught completely off-guard by the extraordinary extent and depth of that win - and this has resulted in a burst of increased volatility in the markets as they adjust to the new reality. Trump’s decision to appoint Stephen Miller as his Chief of Staff shows that he has no intention of moderating his position by working with the Democrats – instead he is doubling down on the extreme right-wing politics which has made him so unpopular.

The initial reaction to the vote was undoubtedly one of relief and euphoria as the Democrats claimed first the House and then the Senate. Then the next day that excitement gave way to fear that they might use their now overwhelming power to somehow curtail or limit AI and the build out of data centres across America.

This led, the next day, to a massive 4,4% drop in the S&P500, completely wiping out the gains of the previous day and taking the NASDAQ particularly, down sharply. Voters and newly elected officials have already passed dozens of local measures restricting data centres (from outright bans to temporary moratoriums), while incoming governors in states like Texas and Georgia have signalled plans to pause or heavily regulate new construction.

Hyperscalers and data centre operators have been funding massive expansions with heavy borrowing and private credit. Rising AI credit costs and heavy debt loads have sparked fears among investors of financial strain, stranded assets, or potential defaults if demand falls short. What if the direction of the technology changes and these huge investments are suddenly irrelevant and there is an unsupportable overhang of debt and abandoned assets?

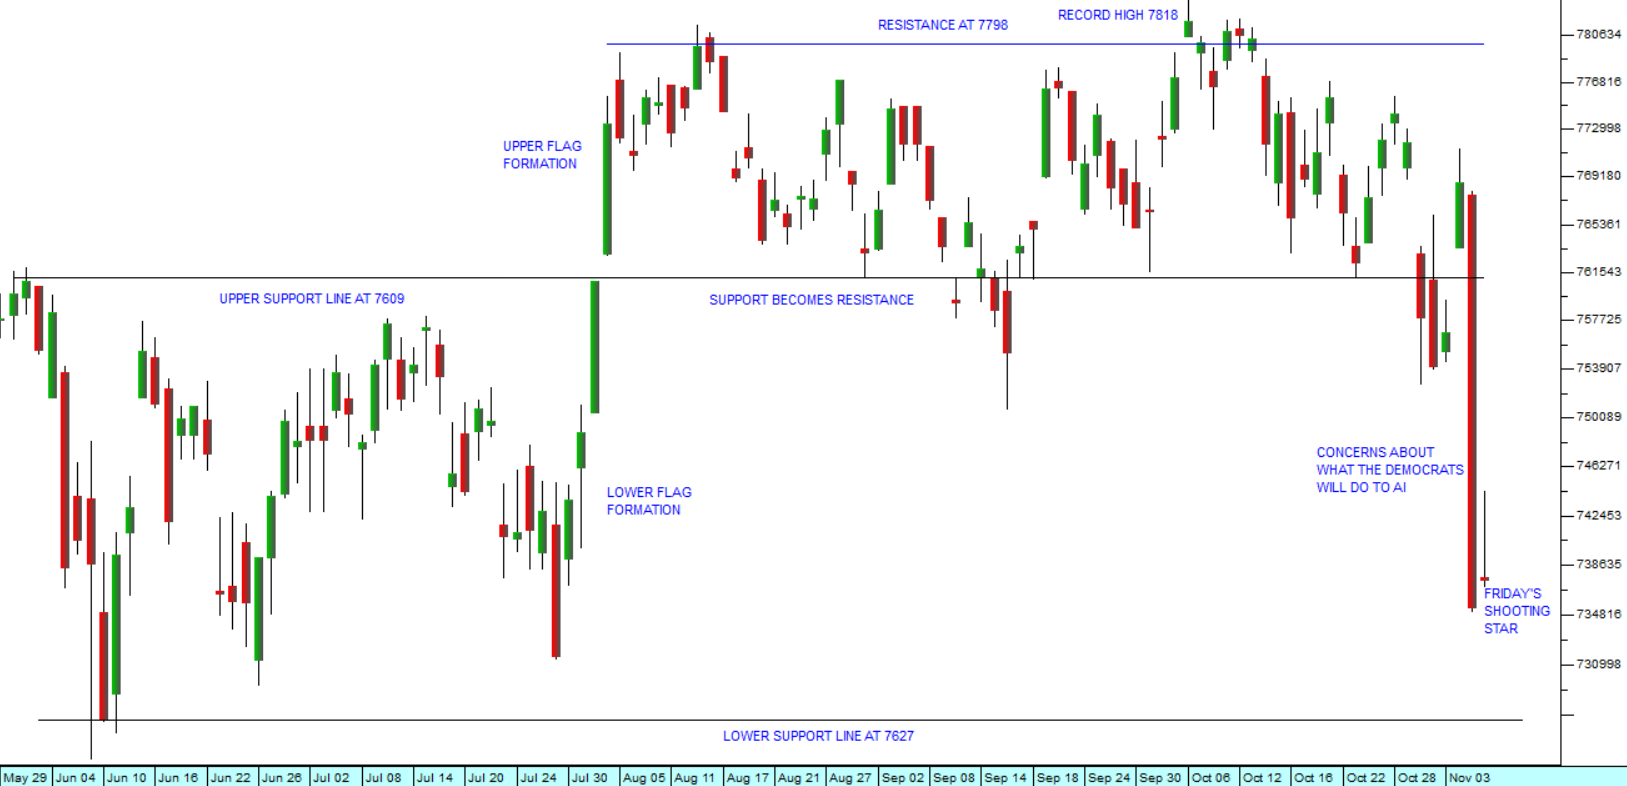
Those fears, added to the fact that tech shares were very already high and due for some kind of correction, has led to a rapid rotation out of AI and into other sectors or into cash. Consider the chart:

S&P500 Index : 29th of May 2026 - 6th of November 2026. Chart by ShareFriend Pro.

Of course, the Anthropic IPO is due to happen on 19th November 2026 and their prospectus has already been issued. They are looking to raise between $80bn and $100bn off a market valuation of between $1,5tr to $2tr. That will now almost certainly have to be curtailed – possibly to as little as $1tr. While Anthropic showed explosive growth - posting $16.3 billion in revenue for the first half of 2026 (up 1,300% year-over-year) - it also recorded an $80.7 billion net loss during that same period.

As a private investor on the JSE watching all this unfold on world markets and with our own election results in the background, you must obviously ask how these things will impact on emerging markets and on South Africa in particular. Our markets, and especially the rand have remained remarkably stable throughout the turbulence. The rand weakened, as far as R16,75 to the US$ and strengthened as far as R16,35, and now has settled in the middle ground of R16,51. This shows that the sharp downward move on Wall Street has not resulted in a huge shift towards risk-off among international investors. The smart money is still buying South African high-yield bonds and our relatively cheap high-quality equities.

On Friday, the US markets stabilised with many investors buying the dip and other even going as far as selling put options for a quick gain if the market recovers some of its former balance. However, the  shooting star formation does not bode well for the coming week. From a purely technical perspective, the lower support line on the S&P at 7626 now becomes important. If that is broken then we are in a full-blown correction.

Against this, we look at the underlying fundamentals of the third quarter S&P500 company earnings and feel that, at the very least, the Thursday sell-off was over-done. At this time 88,2% of S&P500 companies have reported and 82% of those have beaten earnings projections while 74,6% beat revenue expectations. This shows that the bull trend has been very well supported by rising profits across the board. In other words, it does not have the look of a bubble in the throes of bursting. But, in these turbulent times, your ultimate protection remains your stop-loss strategy.

Sasol and the Rising Oil Price  (2026-10-26)

Every major event that happens in the world inevitably offers some kind of investment opportunity for the private investor. The challenge is to work out how best to capitalise on it. So, it was with the war in Iran. At the time that the war began with the Israeli and American bombing raids on 28th…

Every major event that happens in the world inevitably offers some kind of investment opportunity for the private investor. The challenge is to work out how best to capitalise on it. So, it was with the war in Iran.

At the time that the war began with the Israeli and American bombing raids on 28th February 2026, we had already been watching the progress of Sasol for some time. The situation in Iran was tense with riots reported and North Sea Brent had climbed back up to $70 per barrel, but we had no idea that the Americans and Israelis were about to launch a bombing attack.

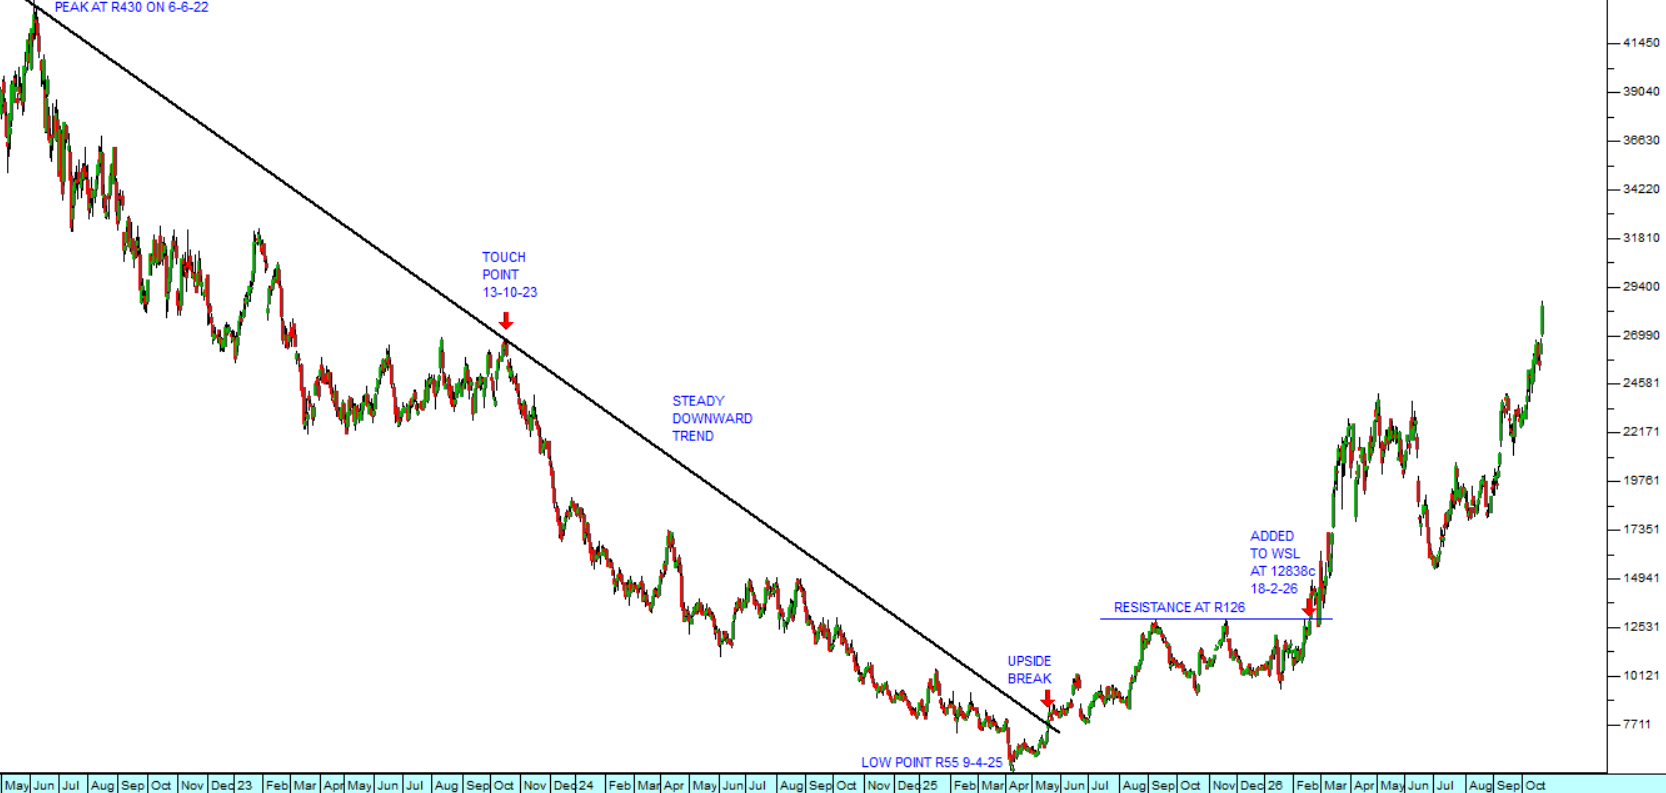
Sasol was always a blue-chip share and has historically occupied a dominant position in South Africa's synthetic fuels industry. It had, however been through some difficult times and the share price had fallen from a high of R430 per share to as low as R55 in April 2025. It then went through an extended period of sideways consolidation. We finally decided to add it to the Winning Shares List (WSL) on 18th February 2026 at a price of R128.36. Technically the share broke above resistance at R126 indicating that something was afoot. Consider the chart:

Sasol (SOL) : May 2022 - 23rd of October 2026. Chart by ShareFriend Pro.

The chart shows Sasol’s long downward trend that began in the middle of 2022, mainly because of the falling price of various grades of oil. North Sea Brent oil fell from a high of $125 per barrel on 8th March 2022 to its cycle low just below $60 per barrel in mid-December 2025. Since Sasol derives more than half of its revenues and profits from the fuel industry, it is directly linked to the price of oil.

Sasol had been recovering but had encountered significant resistance at R126 per share. When it broke decisively above that level, that gave us the signal we needed. Immediately prior to the start of the war the oil price had been climbing, and in January 2026 there were riots in Iran which Trump and Netanyahu used as a pretext to begin the bombing. The price of Brent rose above $70 per barrel on 18th February, before the bombing started, and that triggered a rise in Sasol’s share price. We decided then that Sasol was probably under-valued and due for an upside move.

Sasol’s latest results for the year to 30th June 2026 show the benefits of the rising price of oil. Turnover was up 9% and earnings before interest taxation depreciation and amortisation (EBITDA) was up 17% while the company reduced its debt by 11%.

We do not normally advise investors to buy commodity shares like Sasol because they are riskier, but sometimes they can offer very good capital gains. In the case of Sasol the share appreciated rapidly after we added it to the WSL and then there was a correction as the oil price temporarily fell back in June and July this year. We held on because we thought there might be further upside potential.

The best investment policy is to try to hold onto your shares for at least three years, unless you are moving into a loss position (i.e. you had to execute an early stop-loss sale). This is because if you hold them for less than 3 years the Receiver may seek to declare you to be a share dealer – and then any gain you make will be added to your taxable income and you will be taxed on it at your marginal rate. If you hold for longer than 3 years, then your appreciation is treated as a capital gain for tax purposes and taxed at 18%.

As it turns out holding on to Sasol was the right decision and the share has now appreciated by 134% in about 8 months since we added it to the WSL – which is just shy of 200% per annum.

October Month  (2026-10-19)

There are generally two types of risk in the share market – the risk that a specific share which you have bought falls known as unsystematic risk, and then the risk that the market as a whole falls and drags all your shares down with it - known as systematic risk. The systematic risk that the market…

There are generally two types of risk in the share market – the risk that a specific share which you have bought falls known as unsystematic risk, and then the risk that the market as a whole falls and drags all your shares down with it - known as systematic risk. The systematic risk that the market is in or about to enter a bear trend is obviously a vital consideration for the private investor. During a bear trend about 80% (or more) of shares will fall while only 20% will rise. This means that from a purely statistical point of view it is better for private investors to stay out of the market during bear trends.

It is also very important to be able to distinguish between a correction (which is often a buying opportunity) and a bear trend. The safest approach is always to always buy shares which are rising, in sectors which are rising in a market which is rising. At the same time keeping a strict stop-loss strategy is vital to protect the bulk of your capital. As a private investor you should have an absolute rule that you never lose more than 15% on any share market investment – ever – and that should include your dealing costs. This can only be achieved if you buy free-dealing shares and always adhere to a strict stop-loss strategy.

Today, Monday 19th October 2026 is the exact anniversary of the greatest single day crash in stock market history. Thirty nine years ago, on Monday 19th October 1987, Wall Street collapsed. The S&P500 index fell more than 20% in the day. Other famous bear trends have also begun in October month, including the infamous 1929 crash, the bear trend of the year 2000, the 2008 sub-prime crisis, and the bear trend of 2022 associated with the Ukraine War. So, October month has a bad reputation with investors, and they generally heave a sigh of relief when it is over.

Ominously, Wall Street has been falling over the last week as the Iran war flared up again, pushing the price of North Sea Brent up to nearly $110 per barrel. Consider the chart:

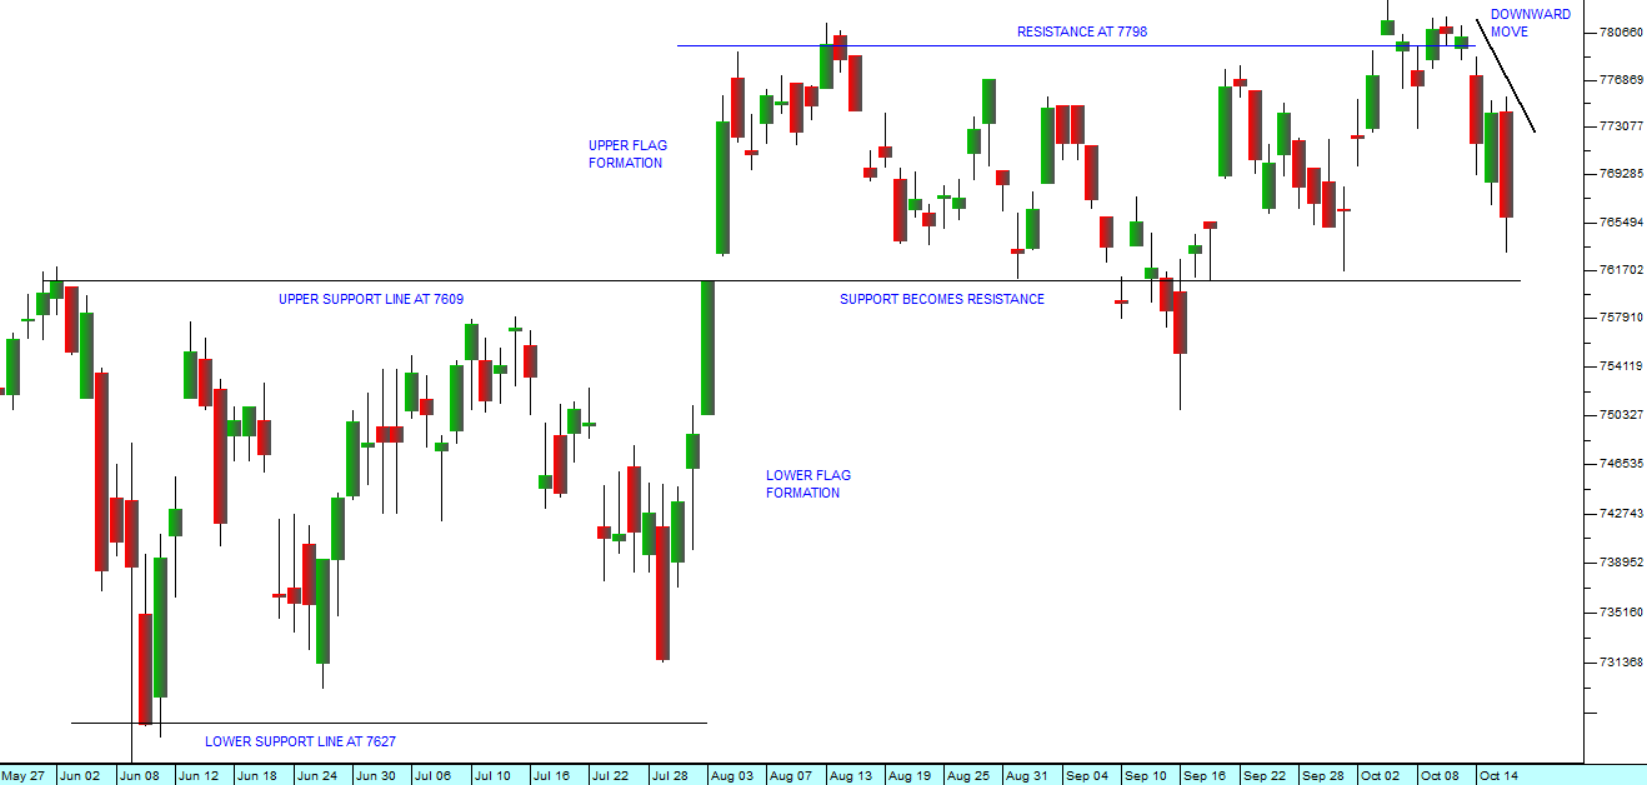
S&P500 Index : 27th of March 2026 - 16th of October 2026. Chart by ShareFriend Pro.

In our analysis, we have drawn your attention to the fact that the S&P500 index has been moving through two sideways markets or flags as the countervailing forces of the rising oil price and the profitability of the artificial intelligence (AI) revolution play out.

The climb in the fuel price is causing a re-evaluation of inflationary risks throughout the world, but especially in America, where the price of petrol has remained stubbornly above $4 per gallon and diesel has hovered above $6 per gallon. With the mid-term elections just weeks away, Republicans and especially Trump are facing a barrage of criticism for their handling of the economy. The Iranians on the other hand are doing everything in their power to keep the oil price at high levels to put the maximum pressure on Trump.

What is notable is that the high oil price appears to be having less and less impact on Wall Street as time goes by. When Trump and Netanyahu began their war with Iran the S&P fell back sharply to 6611 on the 6th of April 2026, and the price of Brent oil went above $110 per barrel. Today Brent is again hovering close to those levels and the S&P has recently managed to reach a new record high at 7818. The world has been facing increased levels of inflation, rising interest rates, and record bond yields - but despite that, AI and corporate profits continue to take the market higher.  

In our opinion, as soon as October month is safely behind us and especially if the mid-term elections have the effect of reducing Trump to a lame dog president, we can look forward to a Christmas rally in the S&P500 during the festive season and into next year. As usual, we strongly advise you to be vigilant and to maintain your stops.

JSE Top 40

104,981.00 (-0.55%)

All Share

112,895.00 (-0.49%)

Financial 15

26,813.00 (+0.37%)

J200
J203
J212
Top Gainers
# Code Name Close (c) % move
1 MTU MANTENGU 11 +22.22%
2 GML GEMFIELDS 76 +10.14%
3 PBT PBT-HOLD 764 +9.14%
Top Losers
# Code Name Close (c) % move
1 MKR MNTKRENEW 2801 -37.01%
2 OAO OANDO 18 -28.00%
3 CNP CANALPLUS 4400 -21.41%

Top Movers – Charts

Top Gainer: MTU
Top Loser: MKR