Market View
J200 106,066.00 -1.57% J203 113,536.00 -1.41% J210 130,428.00 -3.51% J211 120,144.00 +0.35% J212 25,531.00 -0.99% J213 136,304.00 -0.32%
Winning Shares (Top 5)
Code Name Added Price Latest % Gain % Gain/Year
IMP IMPLATS 2025-06-10 15021 23182 +54.33% +43.02%
ANH AB-INBEV 2026-01-31 114756 129696 +13.02% +21.03%
MTH MOTUS 2025-08-27 10360 11323 +9.30% +8.86%
JSE JSE 2024-05-23 9411 15210 +61.62% +26.65%
OCT OCTODEC 2025-08-21 1100 1748 +58.91% +55.27%
Opinions (Top 5)
Code Name Date Action
JBL JUBILEE 2026-09-15 View

Jubilee Metals Group (JBL) is a diversified metals recovery company which re-processes mine waste and surface materials. It is listed both on the London AIM market and on the JSE's Alt-X. It has operations in South Africa, the UK, Madagascar, and Australia - and it is involved in a joint venture in Zambia to produce lead, zinc and vanadium.

The company primarily produces platinum group metals (PGM) and chrome, and its primary asset is a 63% stake in the Tjate project, which is assessed to include the world's largest undeveloped block of platinum ore with an estimated potential of 65m ounces on the Western limb of the Bushveld Igneous Complex. However, in recent years the company has "...pivoted towards a smelting and beneficiation strategy as a cashflow survival strategy." Jubilee has been spending about R154m to consolidate its PGM retreatment business by buying a reprocessing plant and some dumps.

The R154m is being used to buy a chrome processing operation and 1,8m tons of tailings from PlatCro Minerals. It is a low-cost producer, but subject to the vagaries of the platinum and base metals markets. In its results for the six months to 31st December 2025 the company reported revenue of $14m compared with $8,27m in the previous period.

The company made a headline loss of 40c (US) compared with a profit of 0.06c in the previous period. The company said, "Total saleable Cu units produced, including Roan, reached 1 543t (H1 FY2025: 1 419t) an increase of 8.7%". In an update on the 9 months to 31st March 2026 the company reported copper production up 27,8% with Roan production up 112,7%.

The company said, "Commissioning of the expanded Roan Cu concentrate facility is near completion with the ramp- up of dewatered fine Cu concentrate production underway during May 2026". In an update for the year to 30th June 2026 the company reported copper production up 225% while cathode production at Sable for FY2026 increased by 17.5%.

The company said, "During Q4 FY2026, domestic acid availability reduced significantly resulting in tighter supply conditions as well as the cost increasing by in excess of 200%, whilst diesel costs increased by 90%". In our view, this share may be one of the better options in the mining sector, but remains highly volatile and risky.

We suggest waiting for a break up through the share's long-term downward trendline. That has not yet happened but may be imminent. On 7th October 2024 the company announced that it had increased its stake in project "G" to 65% and that it had secured an additional 2 megawatts of power from an IPP.

The war in Iran has negatively impacted the share's price. 

OMN OMNIA 2026-09-15 View

14-09-2026   Omnia (OMN) is a diversified chemicals company supplying products to the agricultural, chemicals and mining industries in South Africa and 48 other countries. The Agricultural division is the leader in fertilizers in Southern Africa. It supplies granular, liquid and speciality fertilizers in Southern Africa, Eastern Africa, Australia, New Zealand, and Brazil.

The mining division is the leading supplier of explosives in South Africa, Mali, Swaziland, Sierra Leone, Malawi, Senegal, Zambia, Zimbabwe, Botswana, Mozambique, and the DRC. The chemicals division is a manufacturer and distributor of speciality, functional and effect chemicals and polymers operating throughout the African continent.

The company gets most of its sales from agriculture for fertilizers and the mining industry for explosives. In its efforts to diversify away from the South African economy, OMN acquired Oro Agri in America for $100m and Umongo Petroleum for R780m. They also commenced the construction of a R630m nitro phosphate plant at Sasolburg.

This company's performance reflects the general performance of the South African economy. It has been very well managed and grows consistently by acquisition and organically, but it is in very tough markets where it has become difficult to make good profits. It is a relatively risky investment and dependent on commodity prices and agriculture - but both of which have done well.

In its results for the year to 31st March 2026 the company reported revenue up 6% and headline earnings per share (HEPS) up 21%. The company said, "This was driven by strong volume and margin growth, supported by the strengthening competitiveness of our core businesses, with both Agriculture and Mining contributing robust earnings, margins and solid cash generation".

Technically, the share was in a downward trend from its peak in May 2022. We recommended waiting for it to break up through its long-term downward trendline, which happened on 18th June 2024 at 6087c and then the share was added to the Winning Shares List (WSL) on 12th January 2026 at 8207c.

The share has since moved up to 10486c (8-6-26). On the 14th of September 2026 the company announced that it had received a firm offer to buy all of its ordinary shares for R21,8bn or 13450c per share. The announcement caused the share price to jump up.

PPH PEPKORH 2026-09-15 View

15-09-2026   Pepkor Holdings (Pep) (PPH), previously known as Pep, is 71,01% owned by Steinhoff International. With the collapse of the Steinhoff group following admissions of "accounting irregularities", the directors of Pep decided to change their name back to Pepkor Holdings to avoid negative publicity.

The group includes Ackermans, PEP Stores and Bradlows and HiFi Corporation. Since the problem began in December 2017, and with the COVID-19 pandemic the share price fell as low as R10 per share in May 2020. Over the next year the share staged a remarkable recovery, more than doubling.

The company raised R1,9bn in an accelerated book-build. The proceeds have been used to reduce debt as a precautionary measure. On 3rd February 2022 the company announced that acquisition of 87% of the Brazilian clothing retailer Avenida. On 13th April 2022 the company announced that its Isipingo distribution centre had suffered significant damage as a result of the flooding in the Natal area and had to be temporarily closed.

The company has adequate insurance to cover the damage. In its results for the six months to 31st March 2026 the company reported revenue up 13,2% and headline earnings per share (HEPS) up 10,3%. The company said, "Strong growth momentum continued in financial services, multiplying customer lifetime value, while the group's informal market business also delivered solid growth".

In an update for the 10 months to 31st July 2026 the company reported revenue up 11,9% and like-for-like sales growth of 3,1%. Technically, the share was in a strong upward trend from May 2023, but has been moving sideways and downwards since it peak in December 2024. We regard this as a blue chip retail counter and we regard it as good value at current levels (1880c on 14-9-26), but suggest that you wait for a new upward trend before investigating further.

We see it as a good quality investment that should benefit from better levels of consumer spending. 

GCT GREENCOAT RENEWABLES 2026-09-15 View

15-09-2026 Greencoat invests in, owns and operates cash generative European renewable energy infrastructure generation and storage assets. The company is involved in gas generation in Ireland and Spain, Nuclear generation in France and Sweden, Biomass generation in Finland and coal generation in Germany.

The company is driven by the European Unions "Net Zero" carbon emissions which is expected to cause the demand for renewable to quadruple between 2024 and 2030. The company owns 40 renewable generation and storage assets in five European market. In its results for the six months to 30th June 2026 the company reported after-tax profit of 11,9m euros and headline earnings per share (HEPS) of 1,08 euro cents compared with a loss of 6,11c in the previous period.

The company said, "Net cash generation of €59.8 million equating to robust net dividend cover of 1.6x, and Illustrative five-year contracted cash flow profile of 73% through to 31 December 2030, providing meaningful revenue visibility". The share came to the JSE of 10th June 2025 and closed on that day at 1845c.

It has since fallen to 1200c (3-3-26) before rallying to current levels around 1473c (14-9-26) and volumes traded have increased to an average of about R1m changing hands every day. The share is clearly a rand hedge, but we suggested that you wait for the upward trend to consolidate before investigating further, but indications are good.

CHP CHOPPIES 2026-09-15 View

15-09-2026   Choppies (CHP) is a Botswana-based grocery retailer with 212 stores which operate in South Africa, Botswana, Zimbabwe, Zambia and Kenya. The company has a primary listing on the Botswana Stock Exchange (BSE) and a secondary listing on the JSE. What is clear is that the grocery market in Southern Africa is fiercely competitive and it will always be difficult for a small operation like Choppies, without the buying power of the larger chains, to compete.

For two years this company was suspended on the JSE (from November 2018) and only resumed trading on 13th November 2020. In its results for the six months to 31st December 2025 the company reported revenue up 8,6% and headline earnings per share (HEPS) down 50%. The company said, "Group profitability was impacted by reduced consumer liquidity driven by the Botswana diamond-market slump and the devaluation of the Pula to combat economic strain from a severe downturn in the global diamond market".

In a trading statement for the year to 30th June 2026 the company estimated that HEPS would fall by between 44% and 54%. Clearly, this company has recovered from a torrid period which saw its shares suspended on the JSE for more than two years. It was originally added to the Winning Shares List (WSL) on 6th March 2025 at 85c and then moved up to 795c by 2nd January 2026.

Since then the share has collapsed back to 89c (14-9-26). We suggest waiting for a clear break up through the 65-Day exponentially smoothed moving average before investigating further. There are only about R20 000 worth of shares changing hands every day on average - which is insufficient volume for even a small investment at the moment. 

Winning Share: IMP
Opinion: JBL
Muddy Waters  (2026-09-14)

It has become difficult to keep up with all the news coming out of America. Trump’s erratic behaviour is combining with other factors to make the systematic risk picture complicated and unpredictable. On the one hand, there have been some excellent results coming out of the S&P500 companies riding…

It has become difficult to keep up with all the news coming out of America. Trump’s erratic behaviour is combining with other factors to make the systematic risk picture complicated and unpredictable. On the one hand, there have been some excellent results coming out of the S&P500 companies riding the wave of AI.

AI Boom Lifts S&P 500 Earnings 32% as 86% of Companies Beat Estimates | Business | CryptoRank.io

Wall Street investors now expect that the earnings of the S&P500 companies will be roughly 32% higher than they were a year ago as second quarter earnings dramatically exceed analysts’ expectations. 86% of S&P500 companies have now reported earnings above forecast. Alphabet reported second-quarter earnings that included a $98 billion gain, while Amazon recorded $53.4 billion in non-operating pre-tax income, primarily related to its Anthropic investments. Nvidia’s revenue in the second quarter was $96,2bn – more than double the same quarter last year.  

On the negative side, the price of North Sea Brent oil spiked up to nearly $110 per barrel last week, but has now fallen back to just below $100. This decline to $100 comes because of new hopes for peace negotiations such as planned meetings between Gulf and Iranian foreign ministers. These hopes helped ease immediate fears of a total, prolonged blockage of the Strait of Hormuz. At the same time, oil producers in the Persian Gulf shifted shipments to alternative pipeline capacities and non-Middle Eastern regions (like the US, Canada, and Ghana) which increased output to bridge supply gaps. Finally, major international bodies, including the International Energy Agency indicated that there was slowing consumption and a broader economic slowdown, and notably reduced oil demand from major importers like China driven partly by the transition to electric vehicles.

In the middle of all this, on Tuesday and Wednesday this week the US Federal Reserve Bank’s monetary policy committee will be meeting to decide on the future course of interest rates, and they will be focusing on these figures.

https://coinpaper.com/35641/stock-market-today-sp-500-nasdaq-jump-1-as-oil-falls-despite-hot-cpi

The US inflation rate for August 2026 came in at 3,4% for the year to the 31st August 2026. This was the same rate as July and shows broad increases across both goods and services with the price of gasoline being the major contributor. In the month itself, inflation was 0,4% because of a 3,9% increase in the price of gasoline.

Following hotter-than-expected August inflation data, market metrics and prediction venues show a massive shift toward monetary tightening. The CME Fedwatch Tool suggests that the probability of a 25 basis point hike in  interest rates is now between 84% and 87% while Polymarket says there is an 81% probability. A hike in interest rates will add to the misery of consumers in America already facing an average price across the country of $4.30 per gallon of petrol.

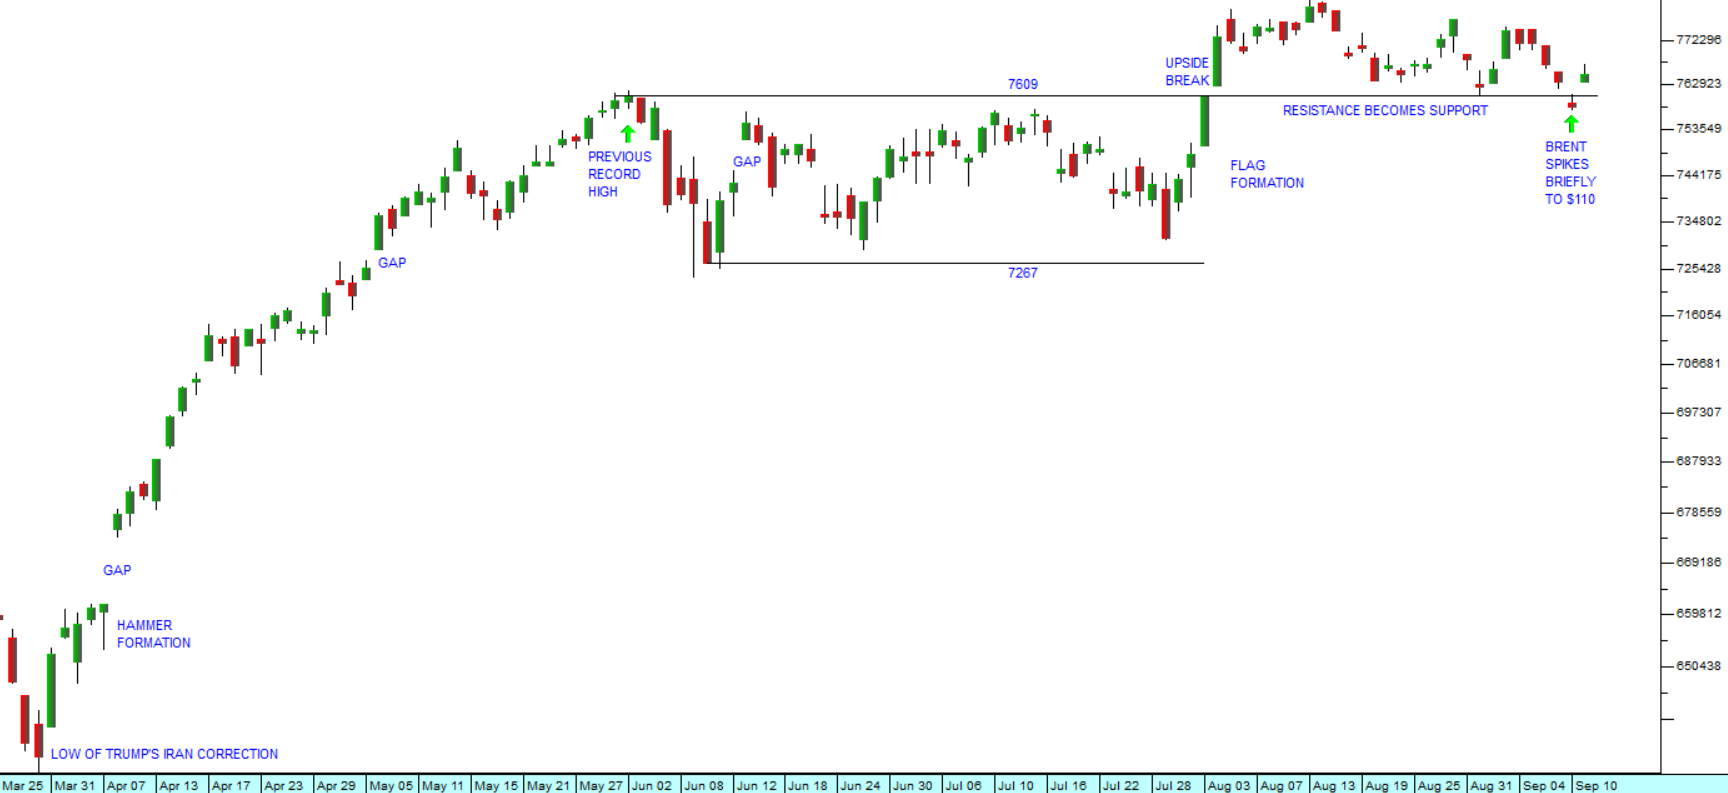
The S&P500 index has been trying to discount all these disparate forces and is basically moving sideways since it broke above the key support/resistance level at 7609. Consider the chart:

S&P500 Index : 25th March 2026 - 11th of September 2026. Chart by ShareFriend Pro.

There can be little doubt about the bullish sentiment which underlies the extended sideways market in the S&P. The news coming from big tech companies appears to be slowly overcoming the bad news coming out of the Middle East. The unexpected spike in the oil price to $110 was short-lived, but it did unnerve the market for a day. That was quickly rectified the next day.

And in the background is the looming mid-term election in America, which is increasingly focusing the Trump camp’s attention, resulting in some radical moves on his part like promising to pay every adult American $5000 if the Republicans win both the House and the Senate. The cost of this is a further $1,23 trillion to be added to the budget deficit already above $40 trillion. He also said that after the elections the petrol price will drop back to $2 per gallon – and anyone who believes that is not following what is happening on the ground.

Trump approval rating hits new low over Labor Day weekend

The Focaldata/Financial Times poll released on September 6, 2026, found that only 32% of Americans now approve of Trump's job performance. Trump's approval rating dropped three points from the previous month, the lowest since the poll series began in May. Critically, his approval among Republicans fell to 72%, a two‑point decline and a new low for that group. The poll was conducted from August 28 to September 2 with 2,178 U.S. adults surveyed. Only 17% of respondents approved of Trump's handling of inflation and the cost of living, while 69% disapproved.

In our view, the Republicans will almost certainly lose the House and the Senate race is now a “toss-up”. If he loses both, we can expect impeachment proceedings to commence promptly.

The S&P500 and markets around the world will ultimately be drawn higher by the AI driven boom in American and elsewhere. We expect new record highs on all indexes in due course.

The Currency  (2026-09-07)

Perhaps the best way to measure the progress of South Africa as a country is to look at our currency – especially against the so-called hard currencies of the Western World. Its strength or weakness gives a very good overall picture of how the country is doing economically, politically and in terms…

Perhaps the best way to measure the progress of South Africa as a country is to look at our currency – especially against the so-called hard currencies of the Western World. Its strength or weakness gives a very good overall picture of how the country is doing economically, politically and in terms of its image with overseas investors.

As an emerging economy, South Africa is not regarded as a poor country, but rather as one which is striving to become first world. For overseas investors this typically means a country and a currency which offers high risk and high potential return. Whereas a 10-year US Treasury Bill can offer the international investor a return of 4,8%, a South African 10-year government bond offers around 8,8% - that is 4% better, if the investor is prepared to take the risk of investing here.

We have a number of advantages over other emerging markets. Perhaps most importantly, we have relatively low inflation. In fact, due to the tireless efforts of Lesetja Kganyago, Governor of the Reserve Bank, our inflation rate is very comparable to many First World countries – and certainly far better than many of the other emerging economies. For example, Turkey’s inflation rate is 31,5%, Argentina is at 33,8% Egypt is at 14,9% and Columbia is at 6%.

We are generally grouped among those less risky emerging economies with lower inflation rates like Brazil (4,6%), India (4,4%), Mexico (3,4%), Indonesia (2,9%), and South Korea (2,8%). These are very comparable to the inflation rates of First World economies like Europe (3,3%), the United Kingdom (2,9%) and America (3,4%).

Approximately $19bn worth of rands are traded in our currency market every day on average. This makes it a highly liquid and very free currency exchange. Overseas investors can quickly take or sell large positions in what is a strong and well-organised market. This has tended to mean that the rand has become a proxy for all emerging economies. When international sentiment is risk-on they pile into our currency and government bonds. When it is risk-off, as it was when Trump began his war with Iran, they sell out quickly.

But overall, for at least the past 17 months the rand has been steadily appreciating against most first world currencies. In our view, this is related to the stabilising impact of the government of national unity (GNU) and the fact that the ANC is no longer in complete control. This together with the various initiatives set in motion by President Ramaphosa have meant that the economic environment has been steadily improving since April 2025.

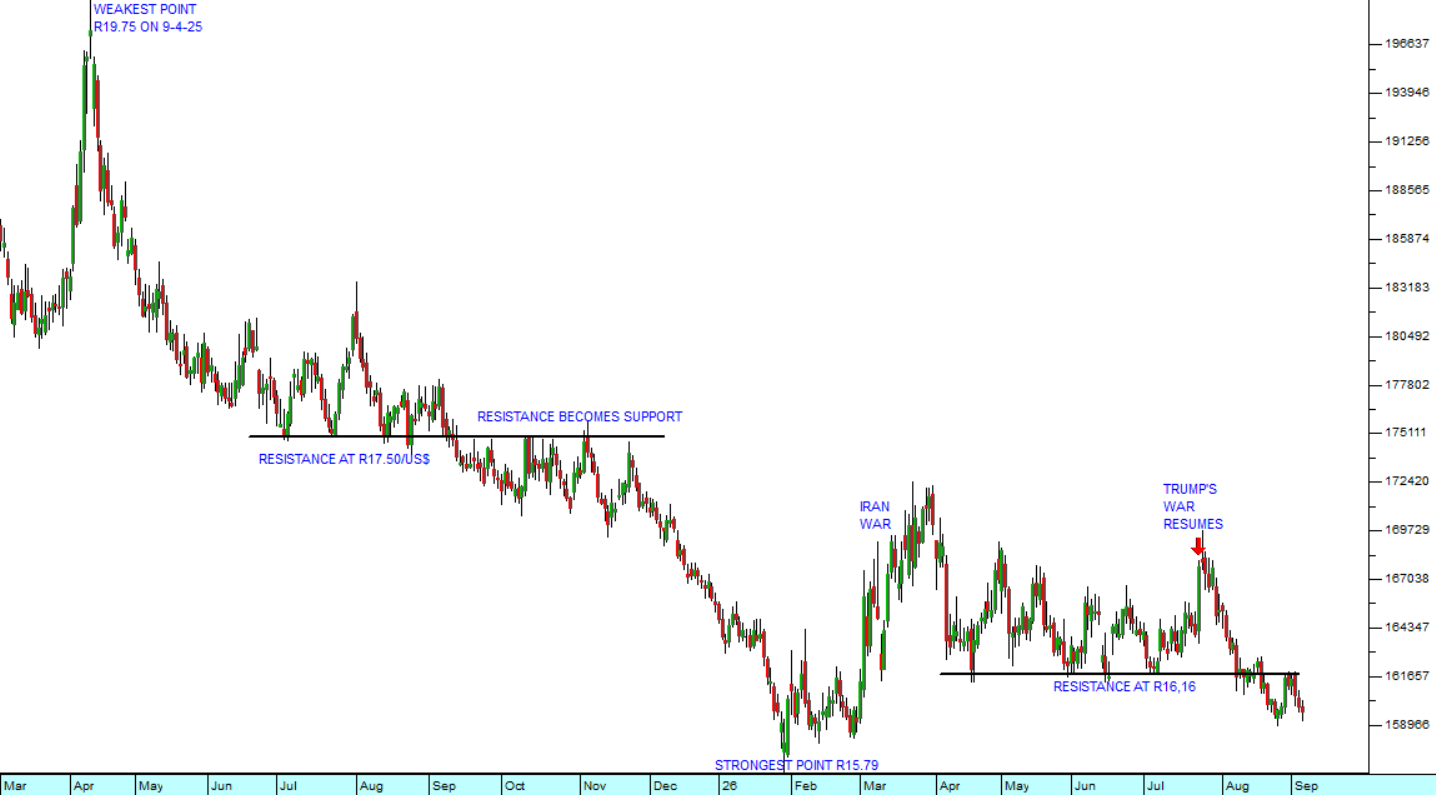
On 10th April 2025 one euro would have cost you R21,90 and today it costs R18,53. On the same day, one British pound would have cost you R25,34 whereas today it costs only R21,56 and of course over the same time period the US dollar has fallen from being worth R19,75 to being worth R15,96. Consider the chart:

South African rand/US dollar : March 2025 - 4th of September 2026. Chart by ShareFriend Pro.

What is significant about this chart is that it clearly shows the steady improvement in international sentiment towards South Africa. The massive, well-informed international investors of the world are betting on our country and putting their money here instead of elsewhere. That is a significant vote of confidence and one which many South Africans caught up in the cut and thrust of daily life here do not appreciate.

In our view, the rand is about to break below its previous cycle low of R15.79 to the US$ made on 29th January 2026. The outcome of the municipal elections on 3rd November 2026 will have a significant impact. If the ANC loses further ground and the DA gains ground (which is what we believe will happen) then you can expect the rand to appreciate further.

A stronger rand is good for everyone in South Africa. It means lower fuel prices, lower inflation, lower interest rates, more stability and a better future for everyone involved in the economy. It is the most telling and reliable indicator of our progress as a nation.

Harmony Takes Off  (2026-08-24)

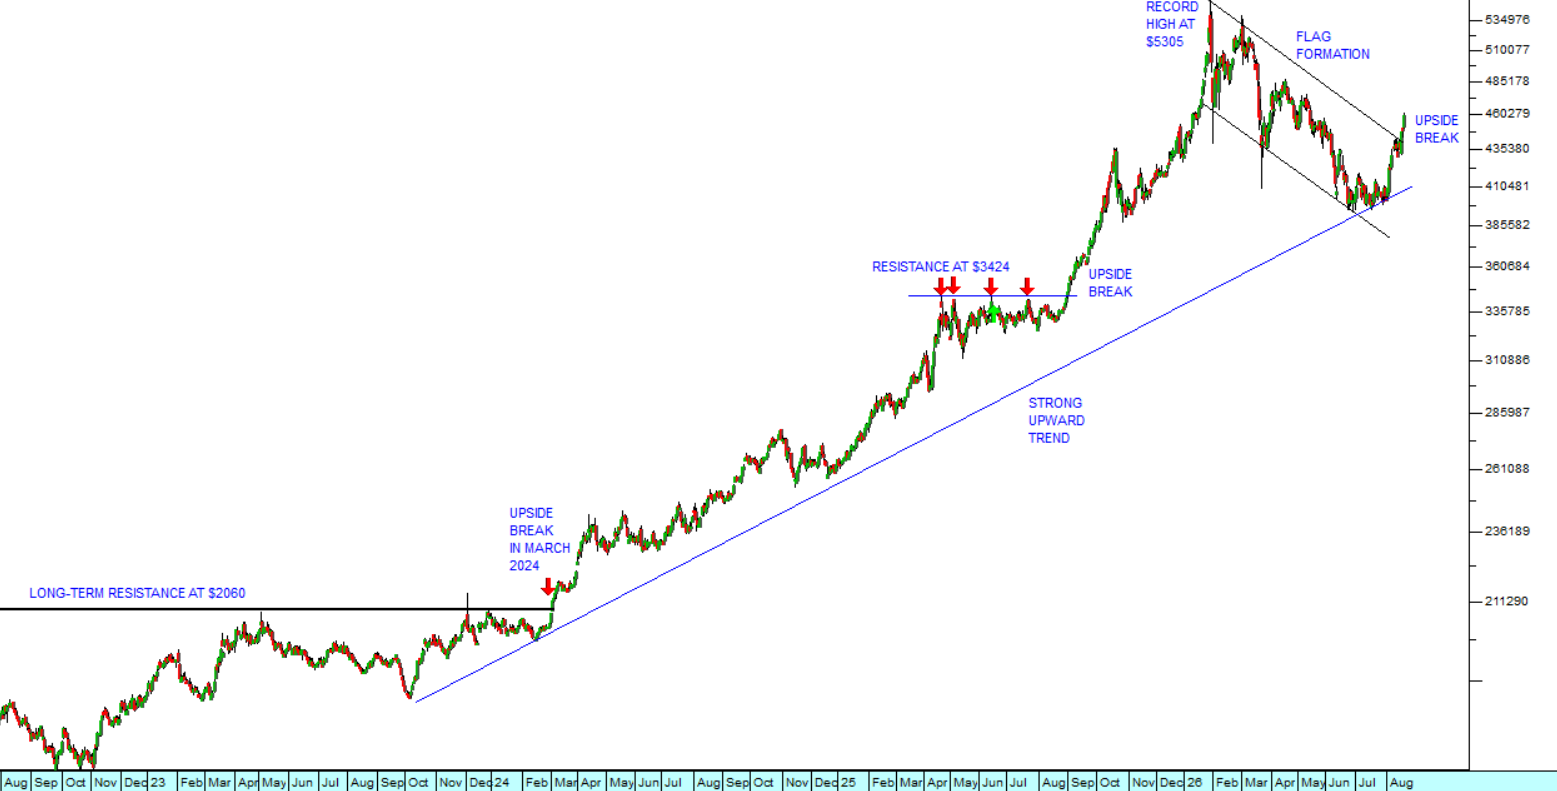
The gold price has been in a persistent correction since its record high on 28th January 2026. It has been in what technical analysts call a descending flag formation which we have drawn you attention to on several occasions. As with any formation we are looking for the direction of the breakout…

The gold price has been in a persistent correction since its record high on 28th January 2026. It has been in what technical analysts call a descending flag formation which we have drawn you attention to on several occasions. As with any formation we are looking for the direction of the breakout from that formation to give a clear idea of the future trend. In the case of gold, we have always been confident that it would break to the upside – and that is what it did last week on 19th August 2026. Consider the chart:

Gold price in US dollars : August 2022 - 21st Of August 2026. Chart by ShareFriend Pro.

The chart shows the US dollar price of gold since August 2022. It broke up out of a long-term sideways pattern in March 2024, and we drew your attention to that in the Confidential Report at the time. The chart shows how the upward trend was paused in 2025 until the precious metal broke above resistance at $3424 and it shows the all-time record high of $5305 on 28th January 2026.

The flag formation has taken place between two parallel downward sloping trendlines, showing how gold lost about $1000 over 5 months then found support before breaking to the upside.

As a private investor you should be thinking about which shares would have enabled you to capitalise on gold’s amazing run – and one of the best was Harmony. Of course, gold shares are always going to be speculative and risky, but under the right circumstances they can provide an excellent long-term investment.

In the case of Harmony, the key, for us, was its purchase of the Mponeng gold mine for $200m in September 2020. This was a very brave, potentially dangerous acquisition and we waited for some time before recognising that they were making a success of it. Mponeng is the deepest mine in the world. It is currently mining at depths of around 3800 meters with plans to go deeper to 4200 meters. This means that it is operating 2 kilometres below sea level from the Highveld near Carletonville. At those depths the grade is excellent - around 11,27 grams per ton – more than double the average grade for South African gold mines. The problem is that mining at those extreme depths is expensive and potentially very dangerous. It is the very definition of a high-risk, high-return investment.

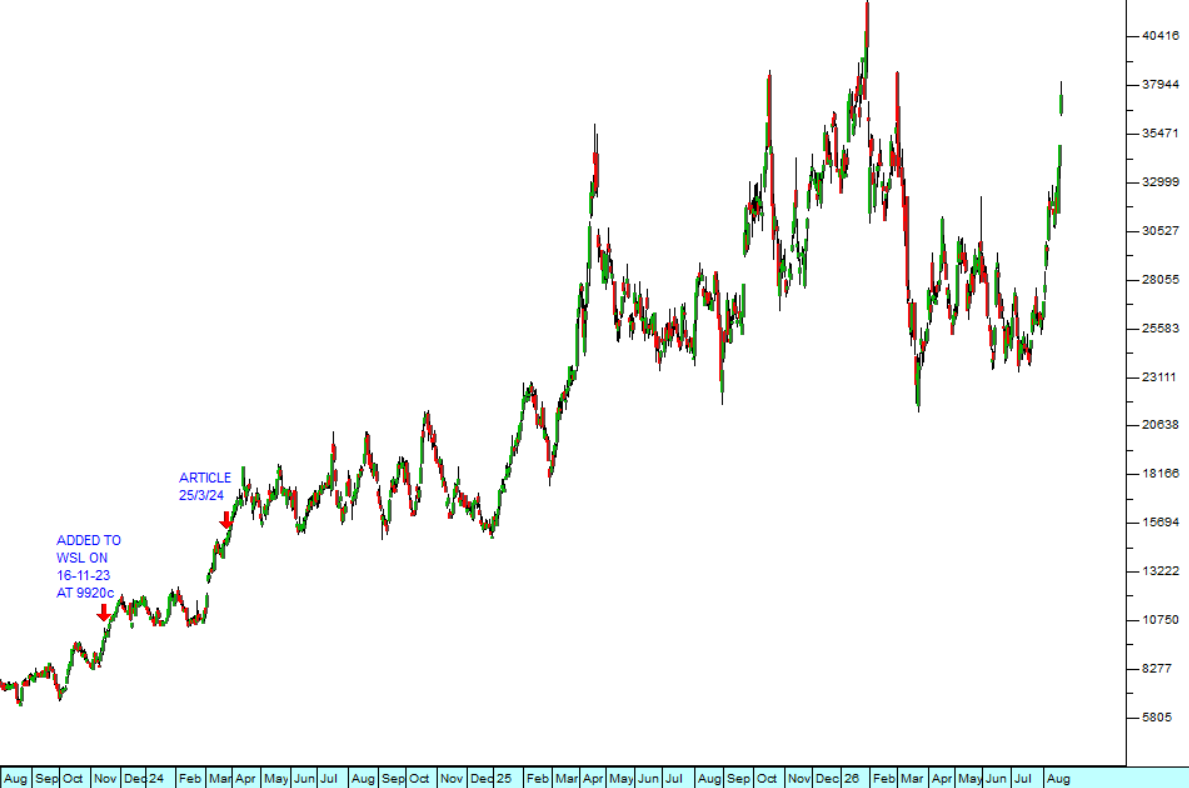
We added Harmony to the Winning Shares List (WSL) on 16th November 2023 at a price of 9920c per share. It reached an all-time high of 40841c on 28th January this year before falling back as gold corrected. Since 3rd August 2026 it has been moving up strongly again as gold recovered. Consider the chart:

Harmony (HAR) : August 2023 - 21st of August 2026. Chart by ShareFriend Pro.

Harmony published an excellent trading statement on Friday last week, predicting that its headline earnings per share (HEPS) would increase by between 90% and 105% in US dollars. 

Altogether, Harmony has risen by more than 250% since we added it to the WSL nearly 3 years ago and we believe it will continue to perform well – but it remains a commodity share and hence both volatile and risky.

JSE Top 40

106,066.00 (-1.57%)

All Share

113,536.00 (-1.41%)

Financial 15

25,531.00 (-0.99%)

J200
J203
J212
Top Gainers
# Code Name Close (c) % move
1 GML GEMFIELDS 74 +19.35%
2 PPR PUTPROP 550 +10.00%
3 SEB SEBATA 210 +7.69%
Top Losers
# Code Name Close (c) % move
1 SOH S-OCEAN 80 -20.00%
2 ENX ENXGROUP 207 -10.00%
3 ISO ASPI 5358 -7.81%

Top Movers – Charts

Top Gainer: GML
Top Loser: SOH